EDIT MODE · click text to change it · press E to exit
Corporate Hierarchy
Michael Ewens and Xavier GiroudColumbia Business School & NBEROctober 2026
Columbia Business School
Corporate Hierarchy

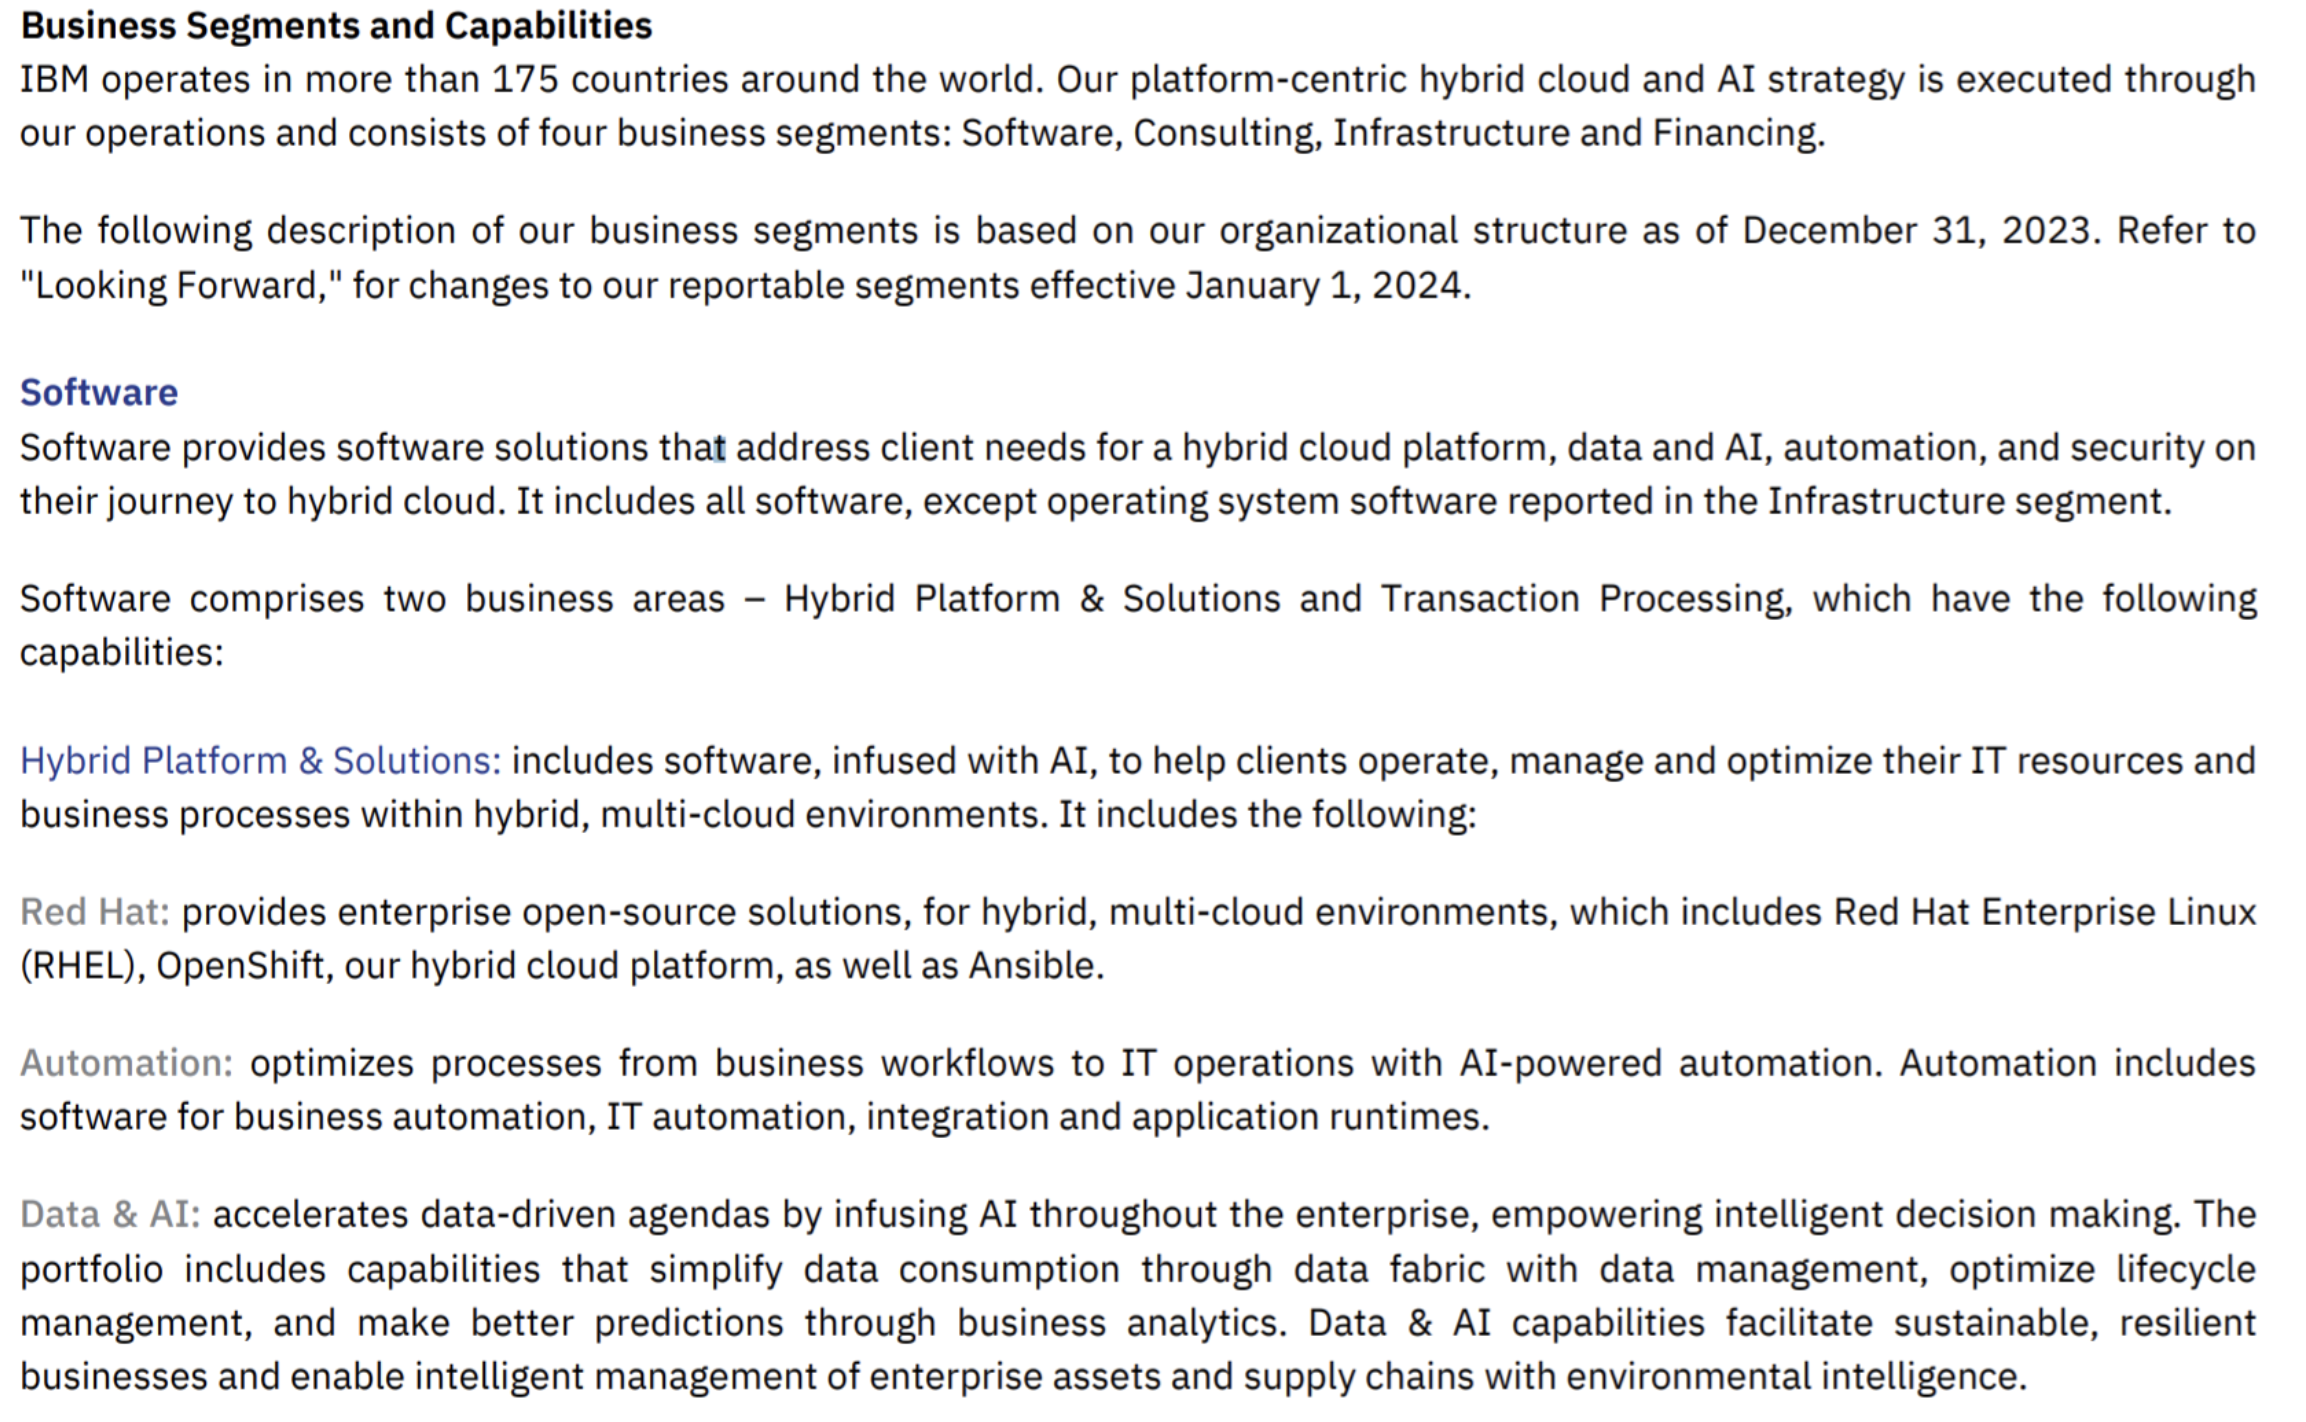
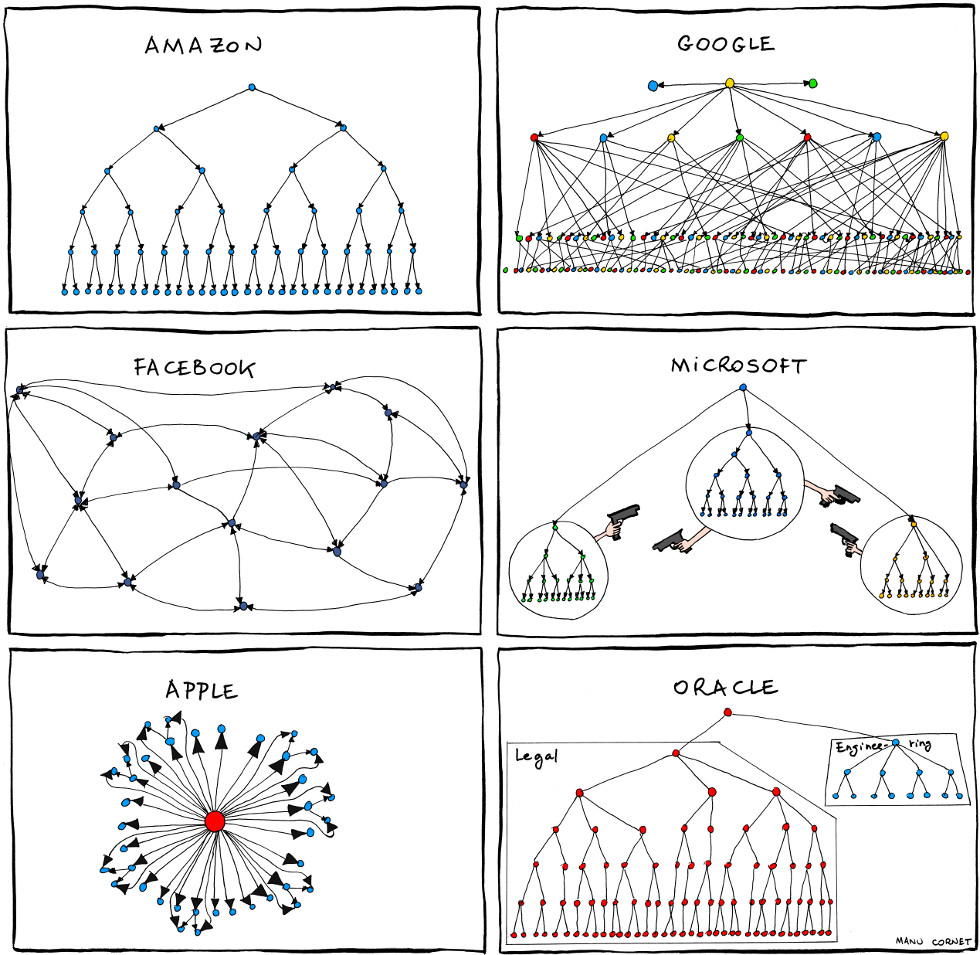
Public firms are complicated
Columbia Business School
Corporate Hierarchy

…and they differ
Columbia Business School
Corporate Hierarchy

The public firm hierarchy

  • Rarely find org. chart in 10-Ks
    • Voluntary disclosure → valuable proprietary information?
  • Few studies of public firms: unique regulatory and financial challenges to interact with hierarchy
  • Empirical literature focuses on the costs of public ownership
Columbia Business School
Corporate Hierarchy

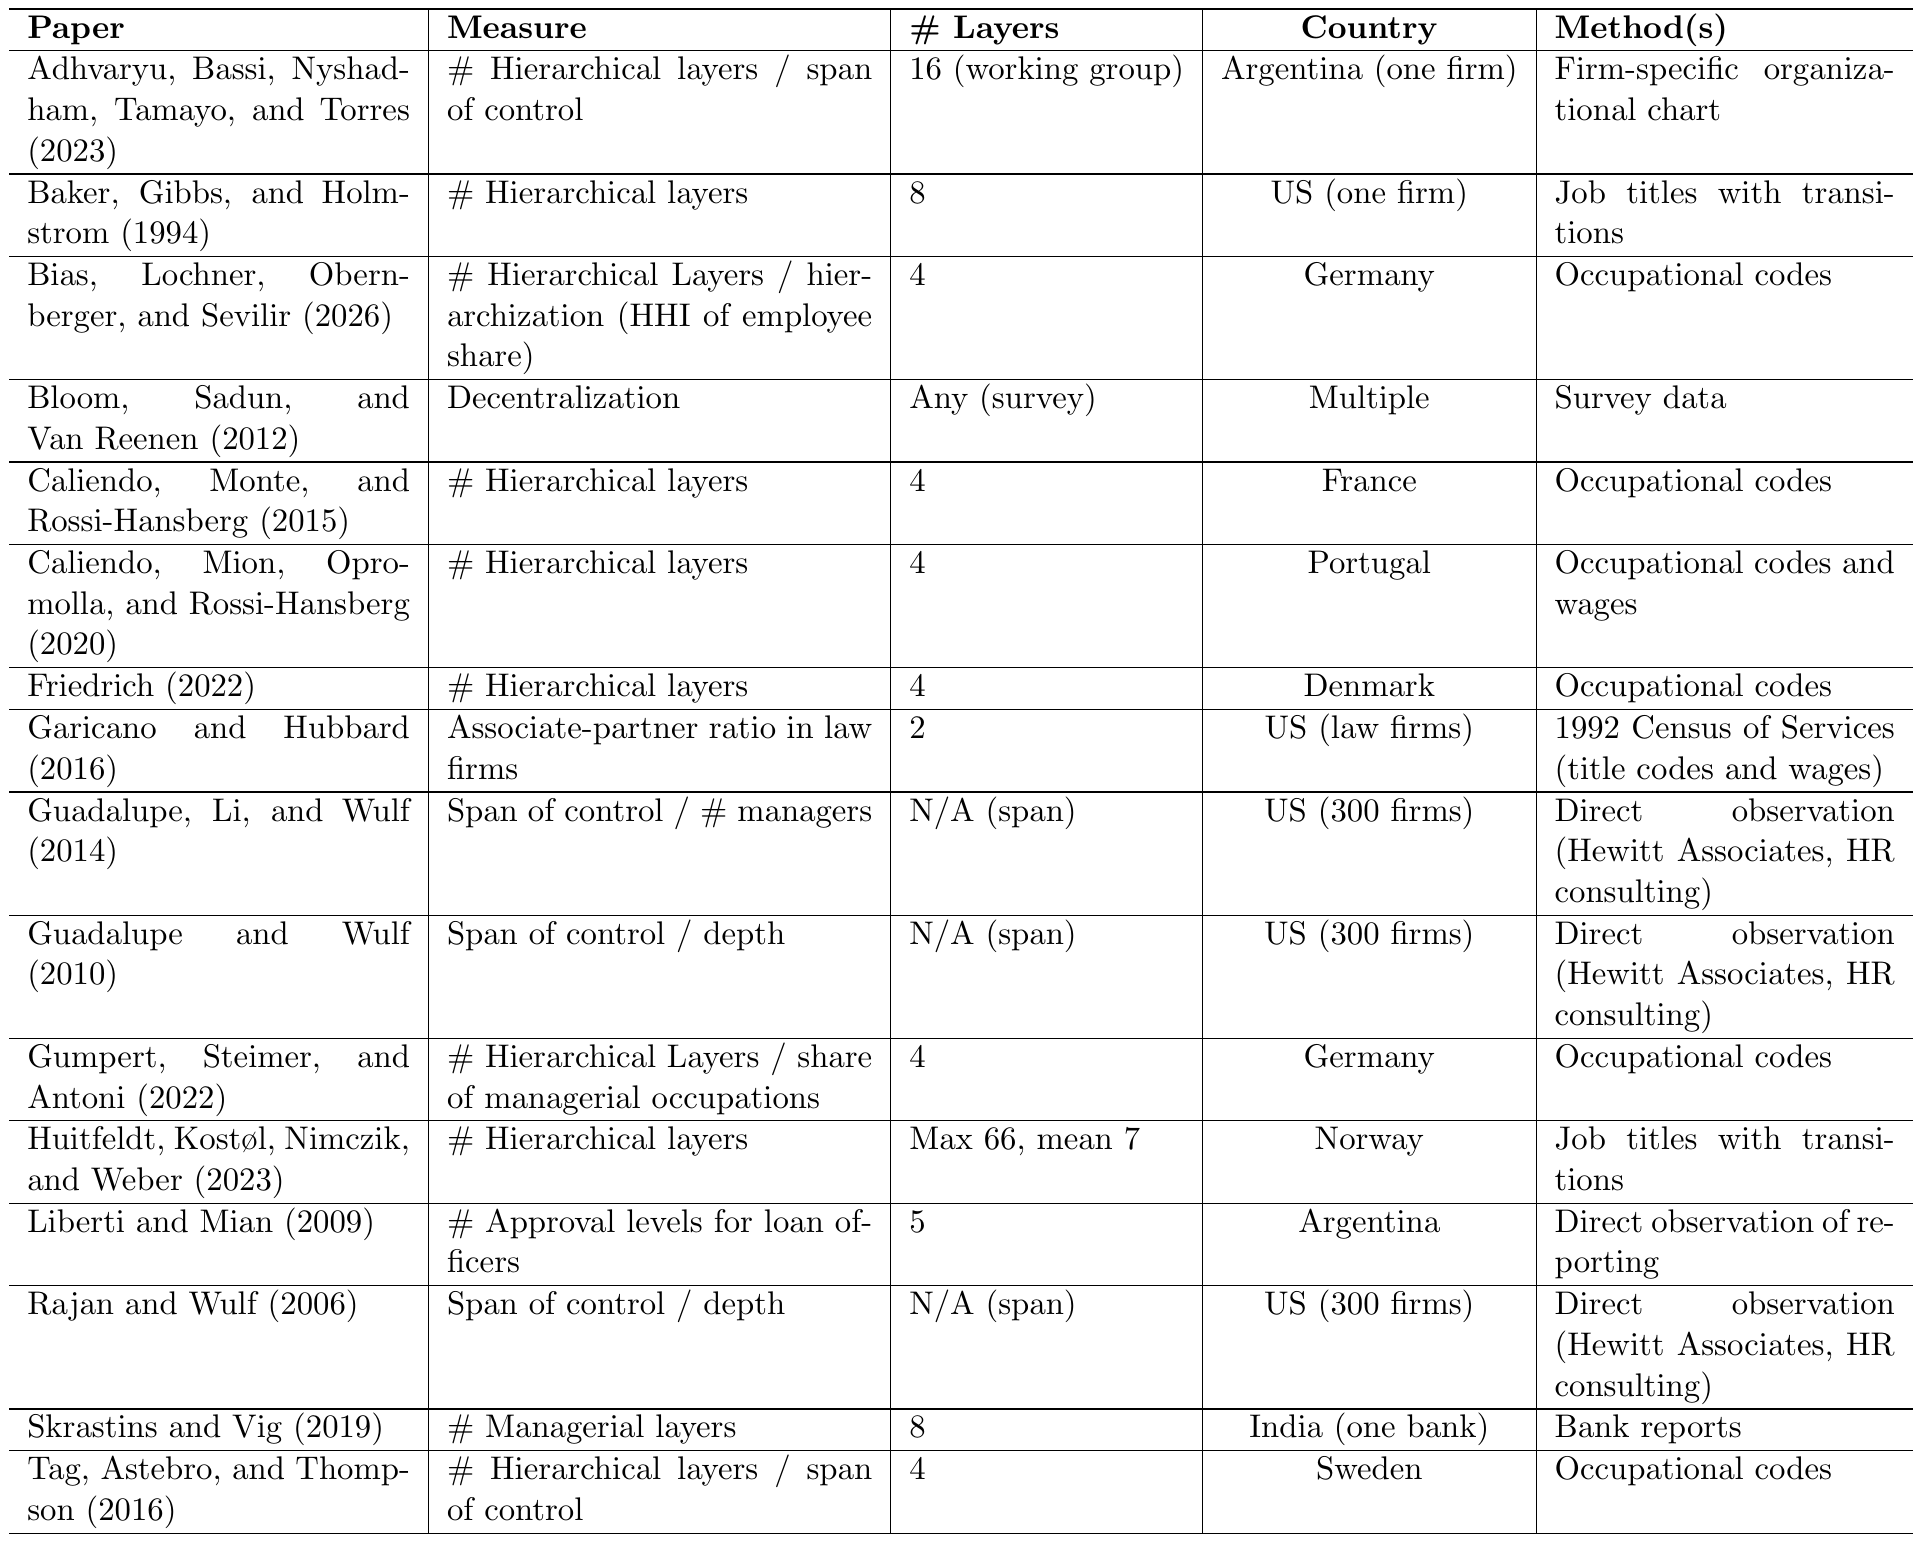
Current approaches to measurement

  • Constrained number of layers (4 to 8 in most papers); no metric for U.S. firms
  • # of CEO reports: view of the top, <1% of employees
  • Homogeneous structures imposed across firms; titles mapped to one occupational code system
Columbia Business School
Corporate Hierarchy

Research questions

What are the determinants and implications of different organizational structures?

  1. How do we measure public firm corporate hierarchies?
  2. What do the hierarchies look like?
  3. Guided by theoretical frameworks, how does corporate hierarchy relate to firm decision-making and outcomes?
Columbia Business School
Corporate Hierarchy

Hierarchies: measurable and important

  • Resumes of 18.1 million workers at 3,454 US public firms
  • Firm-specific algorithm estimates the number of hierarchical layers
  • Average firm has 6.4 layers (median 6), pyramidal shape
  • More layers: longer tenure, more internal promotion, higher operating performance, lower volatility
  • But flatter firms fared better in the Covid crash
  • Product market threats and AI adoption → flatter hierarchies
Columbia Business School
Corporate Hierarchy
Theory
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

What is hierarchy?

“[D]etermine how much each employee knows, how many employees to hire, and how many layers of management to use in production”

Caliendo et al. (2020)

Exist to “solve coordination problems in the presence of specialization” (Garicano 2000)

Columbia Business School
Corporate Hierarchy

What is a layer?

“a group of employees, with similar characteristics summarized in their knowledge, who perform similar tasks within the organization. Conceptually, these layers are hierarchical in the sense that higher layers of management are smaller and include more knowledgeable employees who have as subordinates employees in lower layers.”

Caliendo et al. (2015)

Our challenge: “Dividing the employees in real firms into layers requires some mapping between these concepts and the data.”

Columbia Business School
Corporate Hierarchy

Three classes of models

  • Knowledge hierarchy: managers as problem solvers handling exceptions from below; layers add specialistsGaricano 2000; Garicano and Rossi-Hansberg 2006; Caliendo et al. 2015
  • Information hierarchy: CEO’s span limited by information processing → delegation via layersRadner 1993; Bolton and Dewatripont 1994; Stein 2002
  • Incentive hierarchy: promotions provide incentives; layers create the career path; tournamentsWilliamson 1967; Lazear and Rosen 1981; Malcomson 1984

The tradeoff: gains from specialization vs. costs of communication + fixed cost of training managers

Columbia Business School
Corporate Hierarchy

Testing theory? …no.

Other than knowledge hierarchy, the direct empirical content of these theories is limited

We focus on

  • Documenting facts
  • Correlating with outcomes of interest in corporate finance
  • Let the set of frameworks help us interpret
Columbia Business School
Corporate Hierarchy
Measurement
Using internal labor markets to reveal organizational form
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

Worker flows inside of firms

We implement the Huitfeldt et al. (2023, J of Econometrics) method

Steps:

  1. Identify largest internal labor market
  2. Rank jobs/roles within the largest ILM
  3. Cluster roles using ranks and signals of lateral moves

Intuition: job transitions reveal the ranking of titles and cluster based on similar ranks

Columbia Business School
Corporate Hierarchy

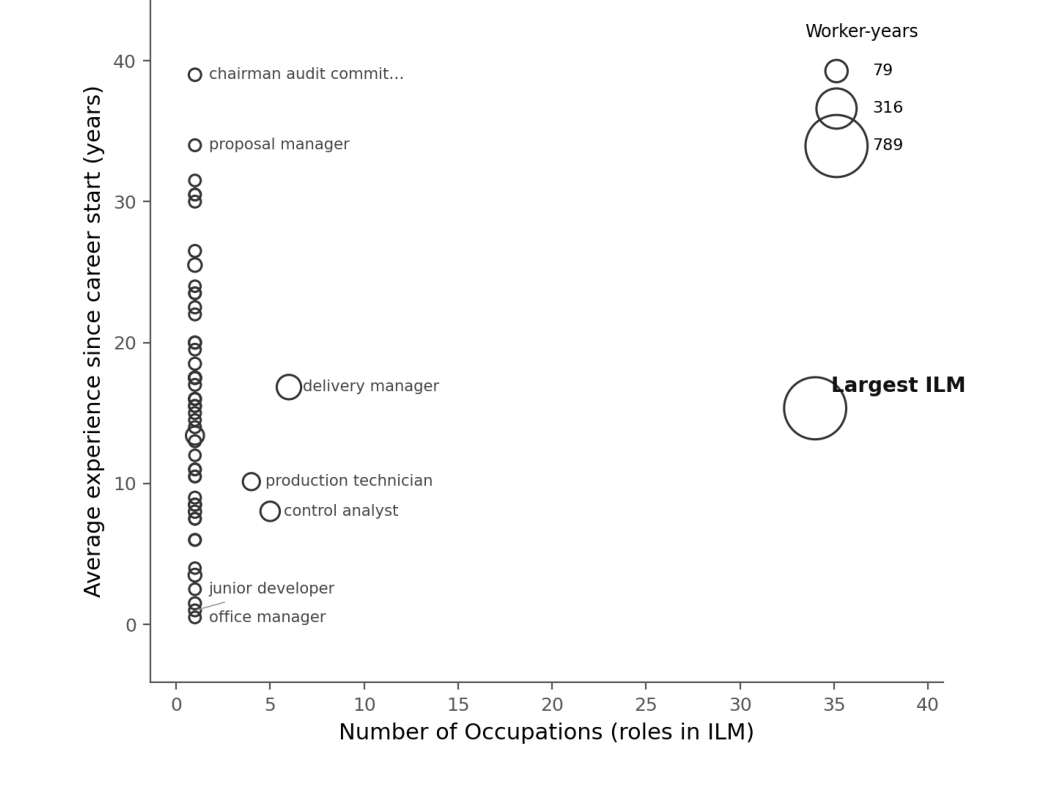
Job promotion network

  • Jobs connected through promotion reveal internal labor markets (ILM)
  • Estimator can be run on any ILM
  • Focus on the largest ILM as measured by % of roles
  • What sits outside: board members, lawyers, lobbyists, front-line workers
Columbia Business School
Corporate Hierarchy

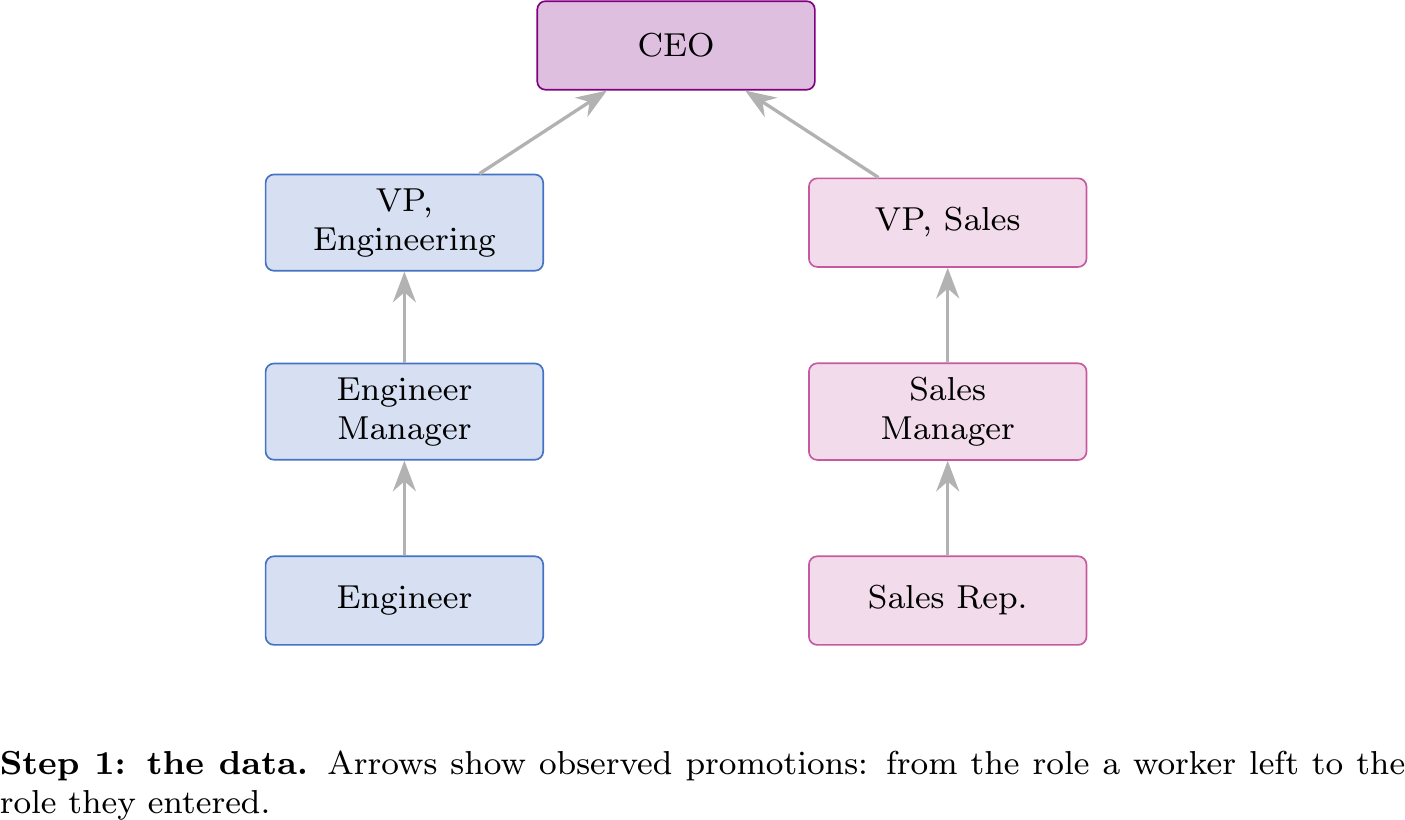
Toy example: the observed promotions
Columbia Business School
Corporate Hierarchy

Rank the roles
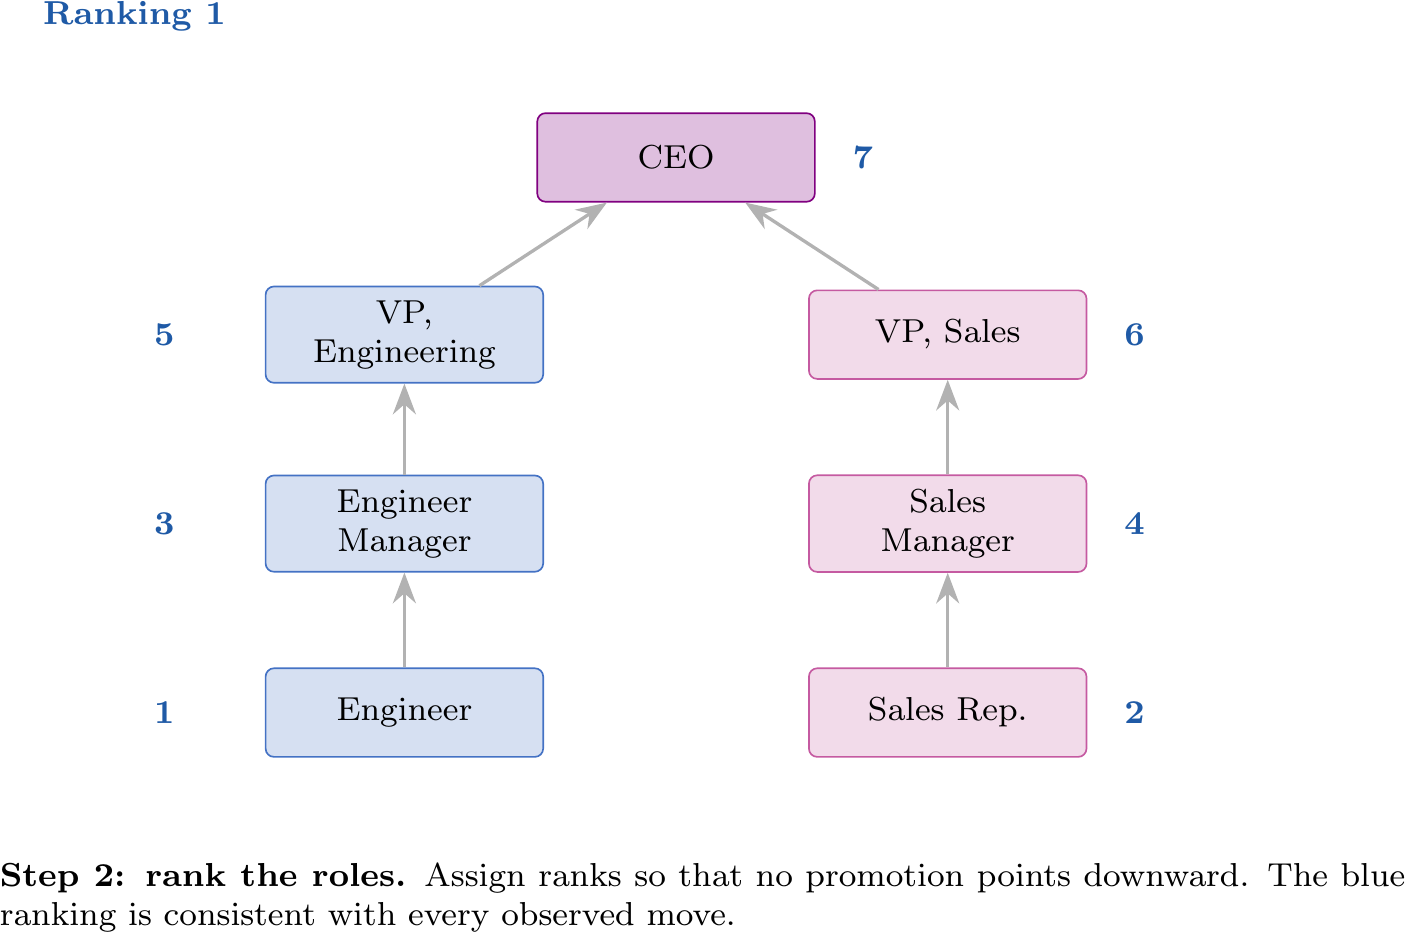
Columbia Business School
Corporate Hierarchy

Why swap? Revealing the job ladder

  • Swaps test where a role sits: lateral roles can trade places without breaking any promotion; true ladder steps cannot
  • A violation: a promotion that points down the ordering
    • The best ranking has the least violations
  • Repeatedly propose swaps and accept any that does not increase violations
  • In the set of minimum violations:
    • Roles that swap freely land at similar average ranks
    • Roles that cannot swap keep their separation
Columbia Business School
Corporate Hierarchy

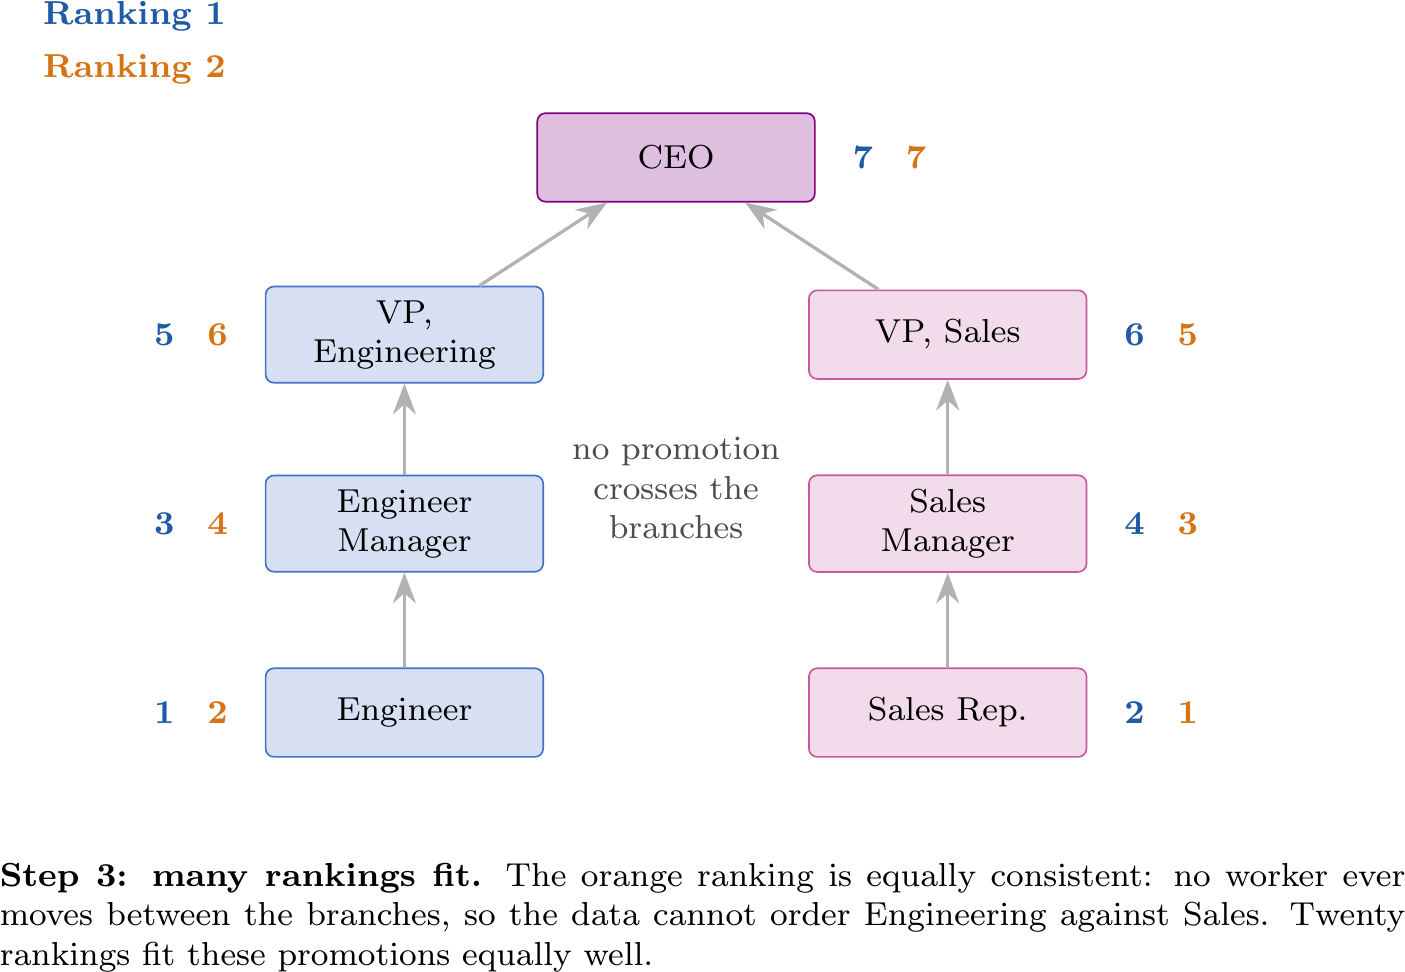
Many rankings fit equally well

  • Swapping the Engineering and Sales branches rank by rank breaks no promotion
  • Every zero-violation ranking is equally consistent: the minimum-violation set
Candidate rankingViolations
Ranking 1 (blue)0
Ranking 2 (orange)0
VP, Sales below Sales Manager1
CEO at the bottom2
Columbia Business School
Corporate Hierarchy

Average ranks, then cluster into layers
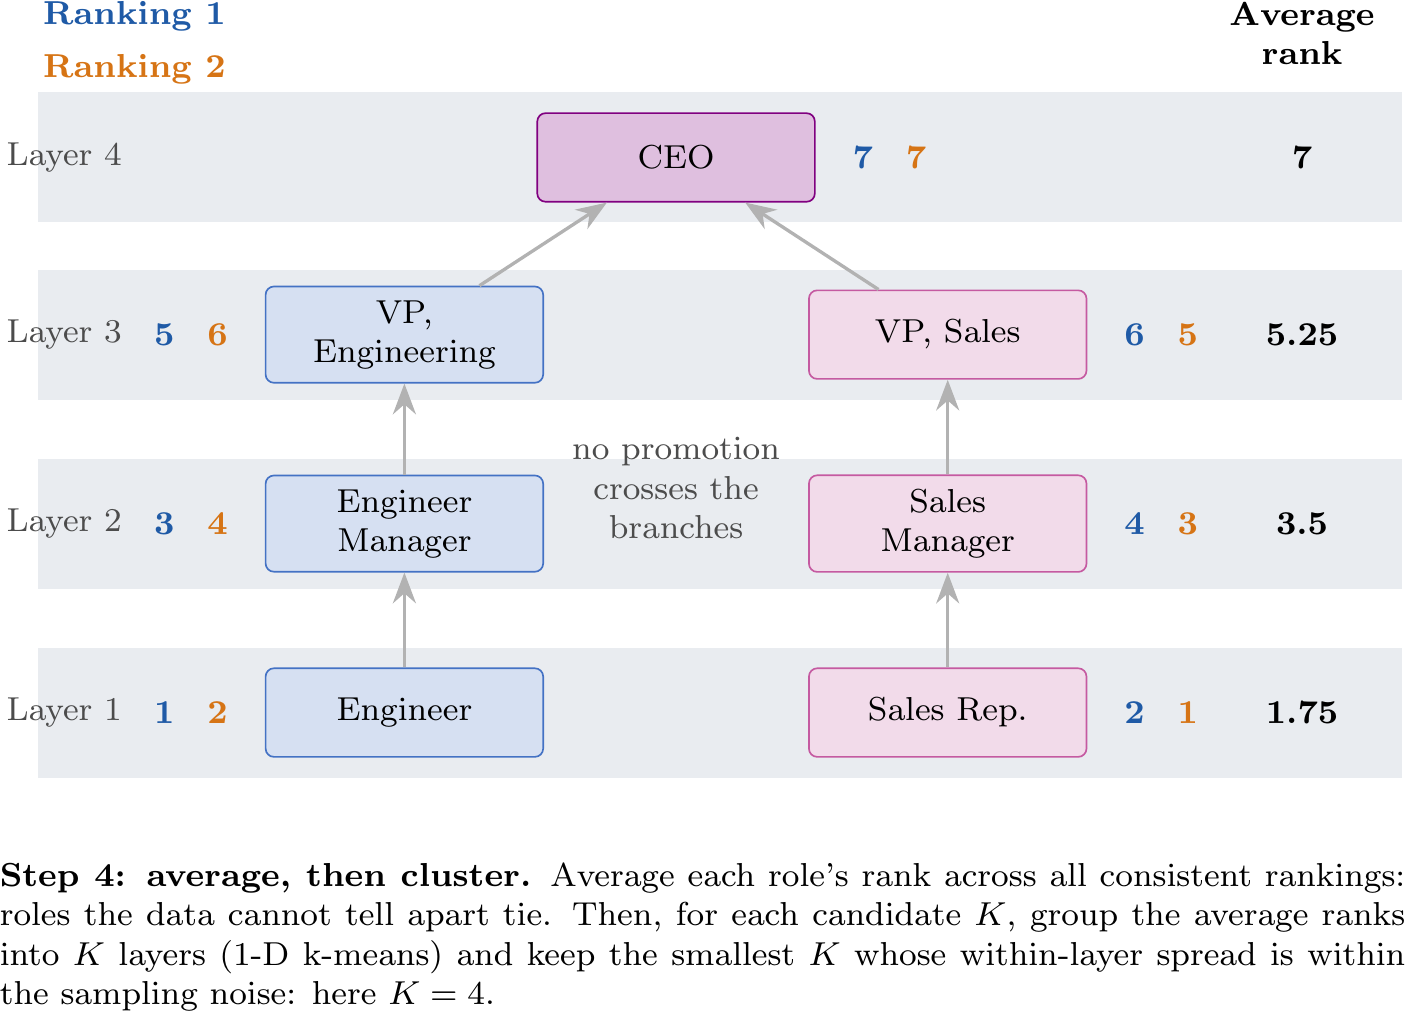
Columbia Business School
Corporate Hierarchy

Choosing the number of layers

Where do the cuts go? (K given)

  • Repeated search runs give each role a mean rank and an uncertainty
  • Line the roles up by mean rank
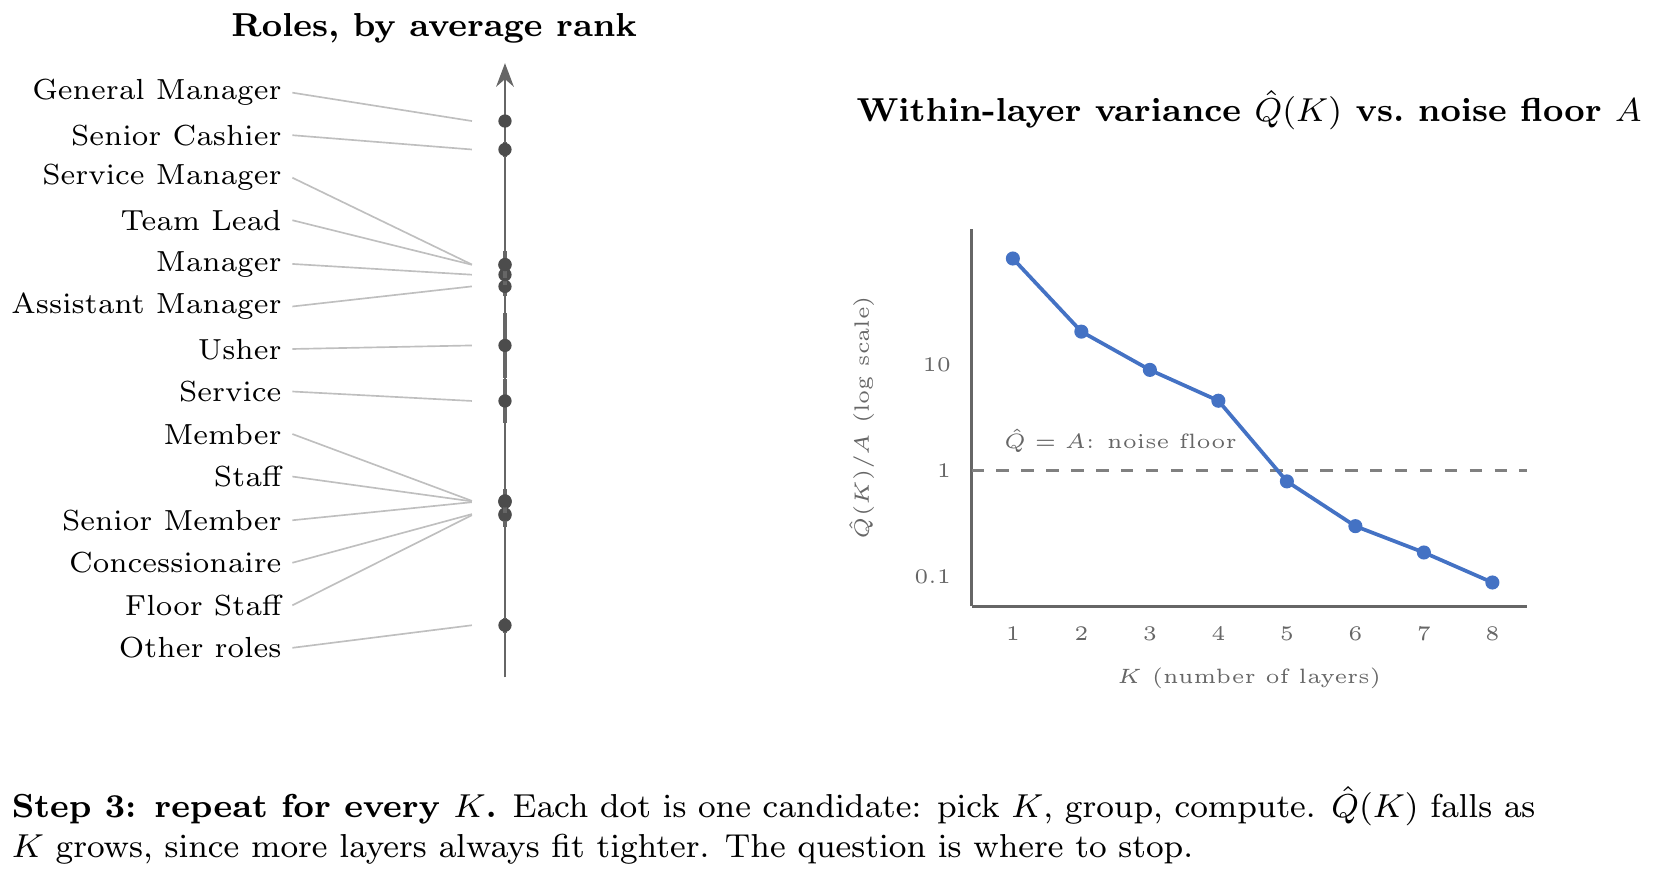
  • 1-D k-means: try every cut into K contiguous bands; keep the one with the least within-layer variance

How many layers?

  • Noise floor A: the average squared rank uncertainty of the roles
  • Roles the data cannot place at all (indistinguishable from random) are left out of A
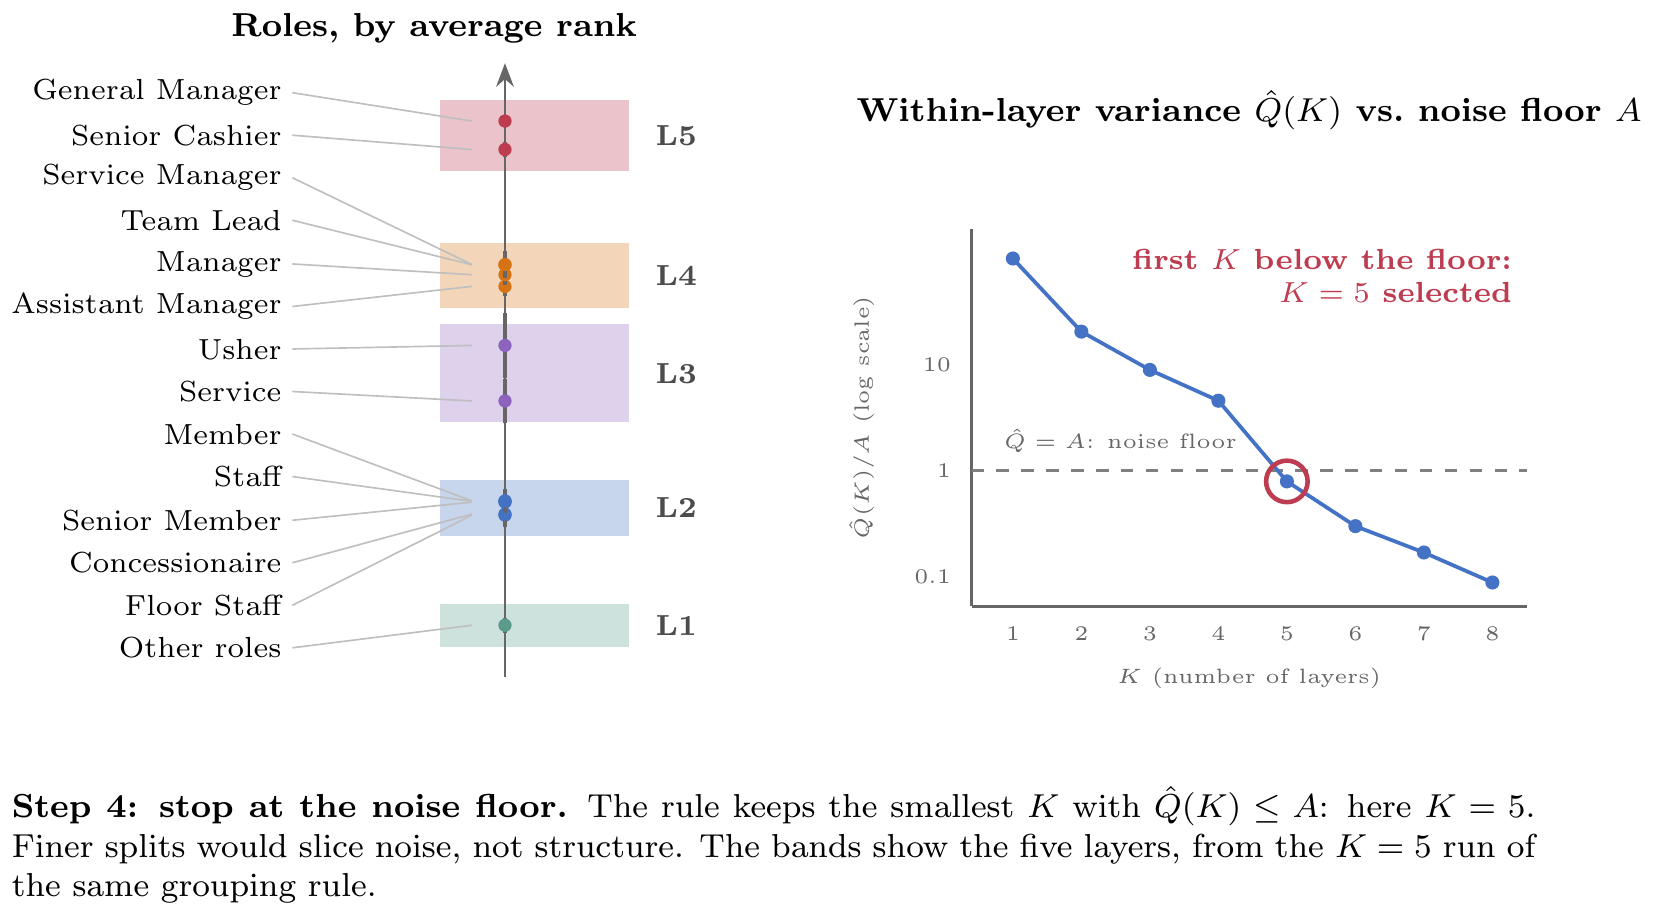
  • K = the smallest number of layers whose within-layer variance is at or below A
Columbia Business School
Corporate Hierarchy

Estimated ranks with uncertainty

Example: Regal Entertainment
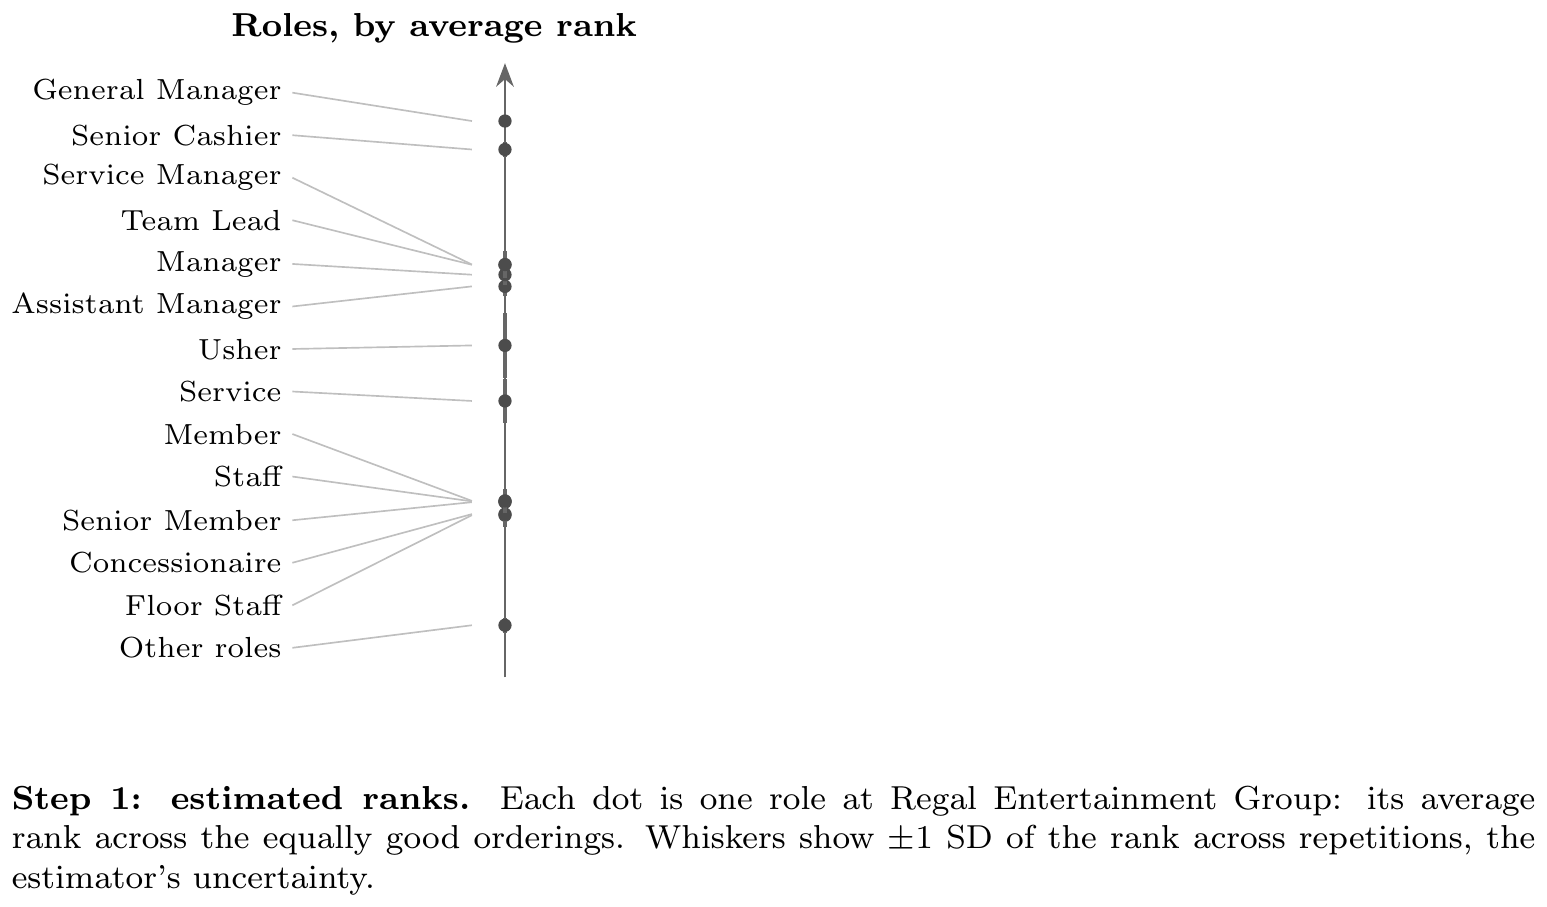
Columbia Business School
Corporate Hierarchy

Group roles for one candidate K
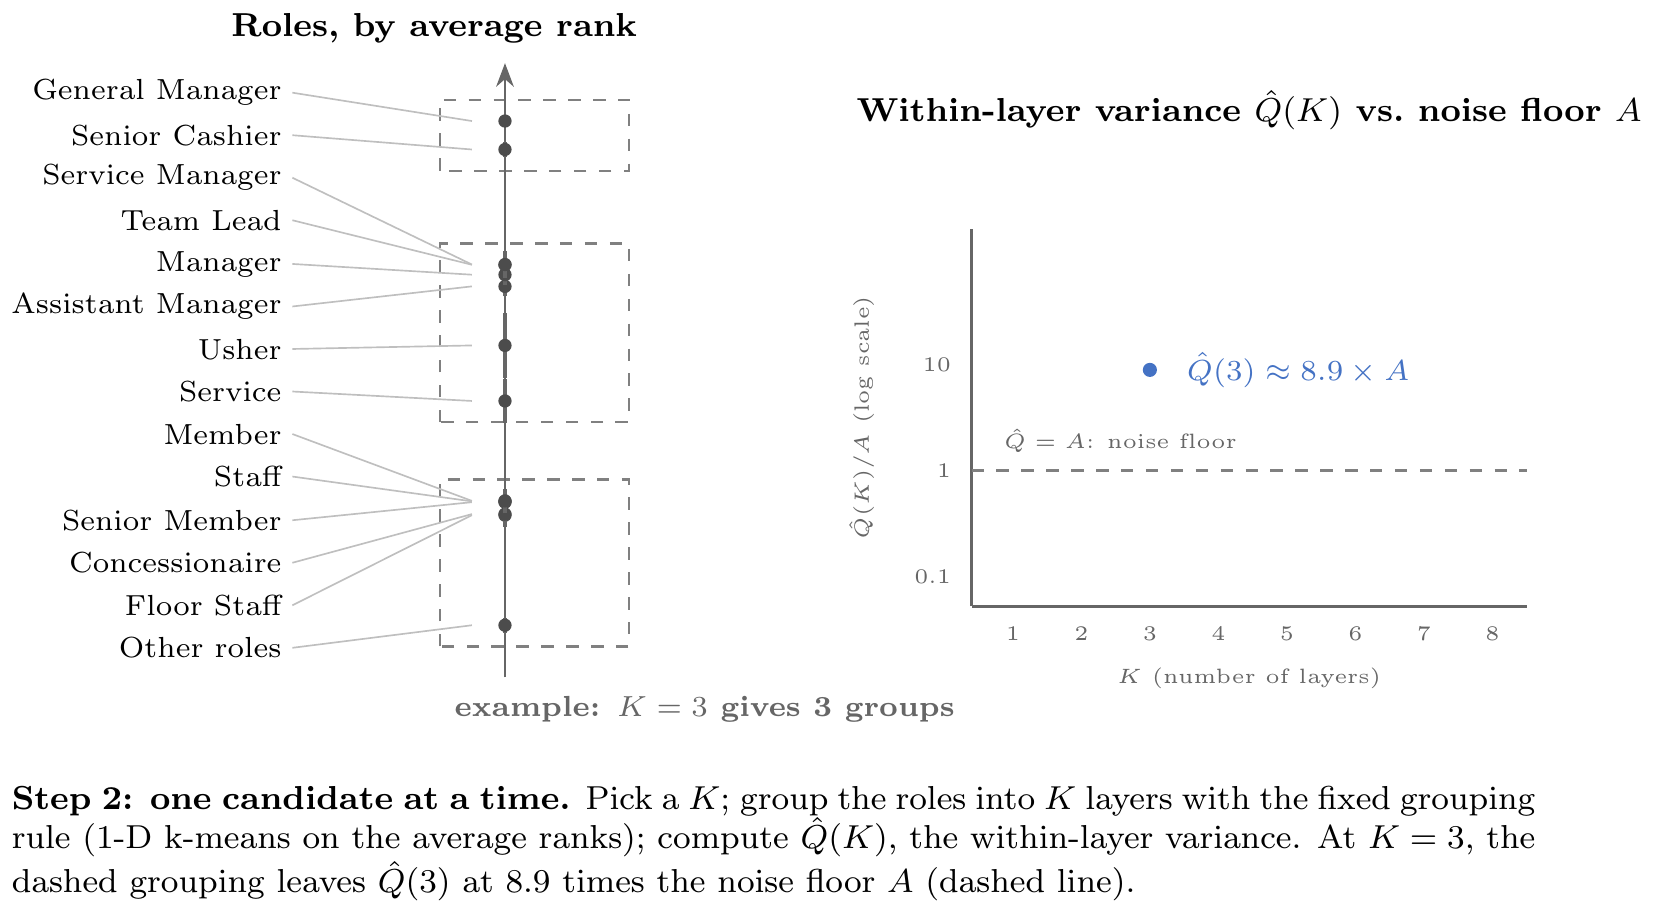
A = noise floor, the average squared rank uncertainty across roles (0.100). Q̂(3) = 0.885 is the spread left inside the three layers. Their ratio is 8.9: three layers leave about nine times the noise unexplained.

Columbia Business School
Corporate Hierarchy

Repeat for every candidate K
Columbia Business School
Corporate Hierarchy

Stop at the noise floor
Columbia Business School
Corporate Hierarchy
Data and representativeness
Worker job histories and public firms
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

Goal: worker histories with public firms

  • Two vendors: Revelio (2013–2024, default) + CoreSignal (longer histories; used where Revelio inadequate)
Titles → Roles
Columbia Business School
Corporate Hierarchy

Sample construction

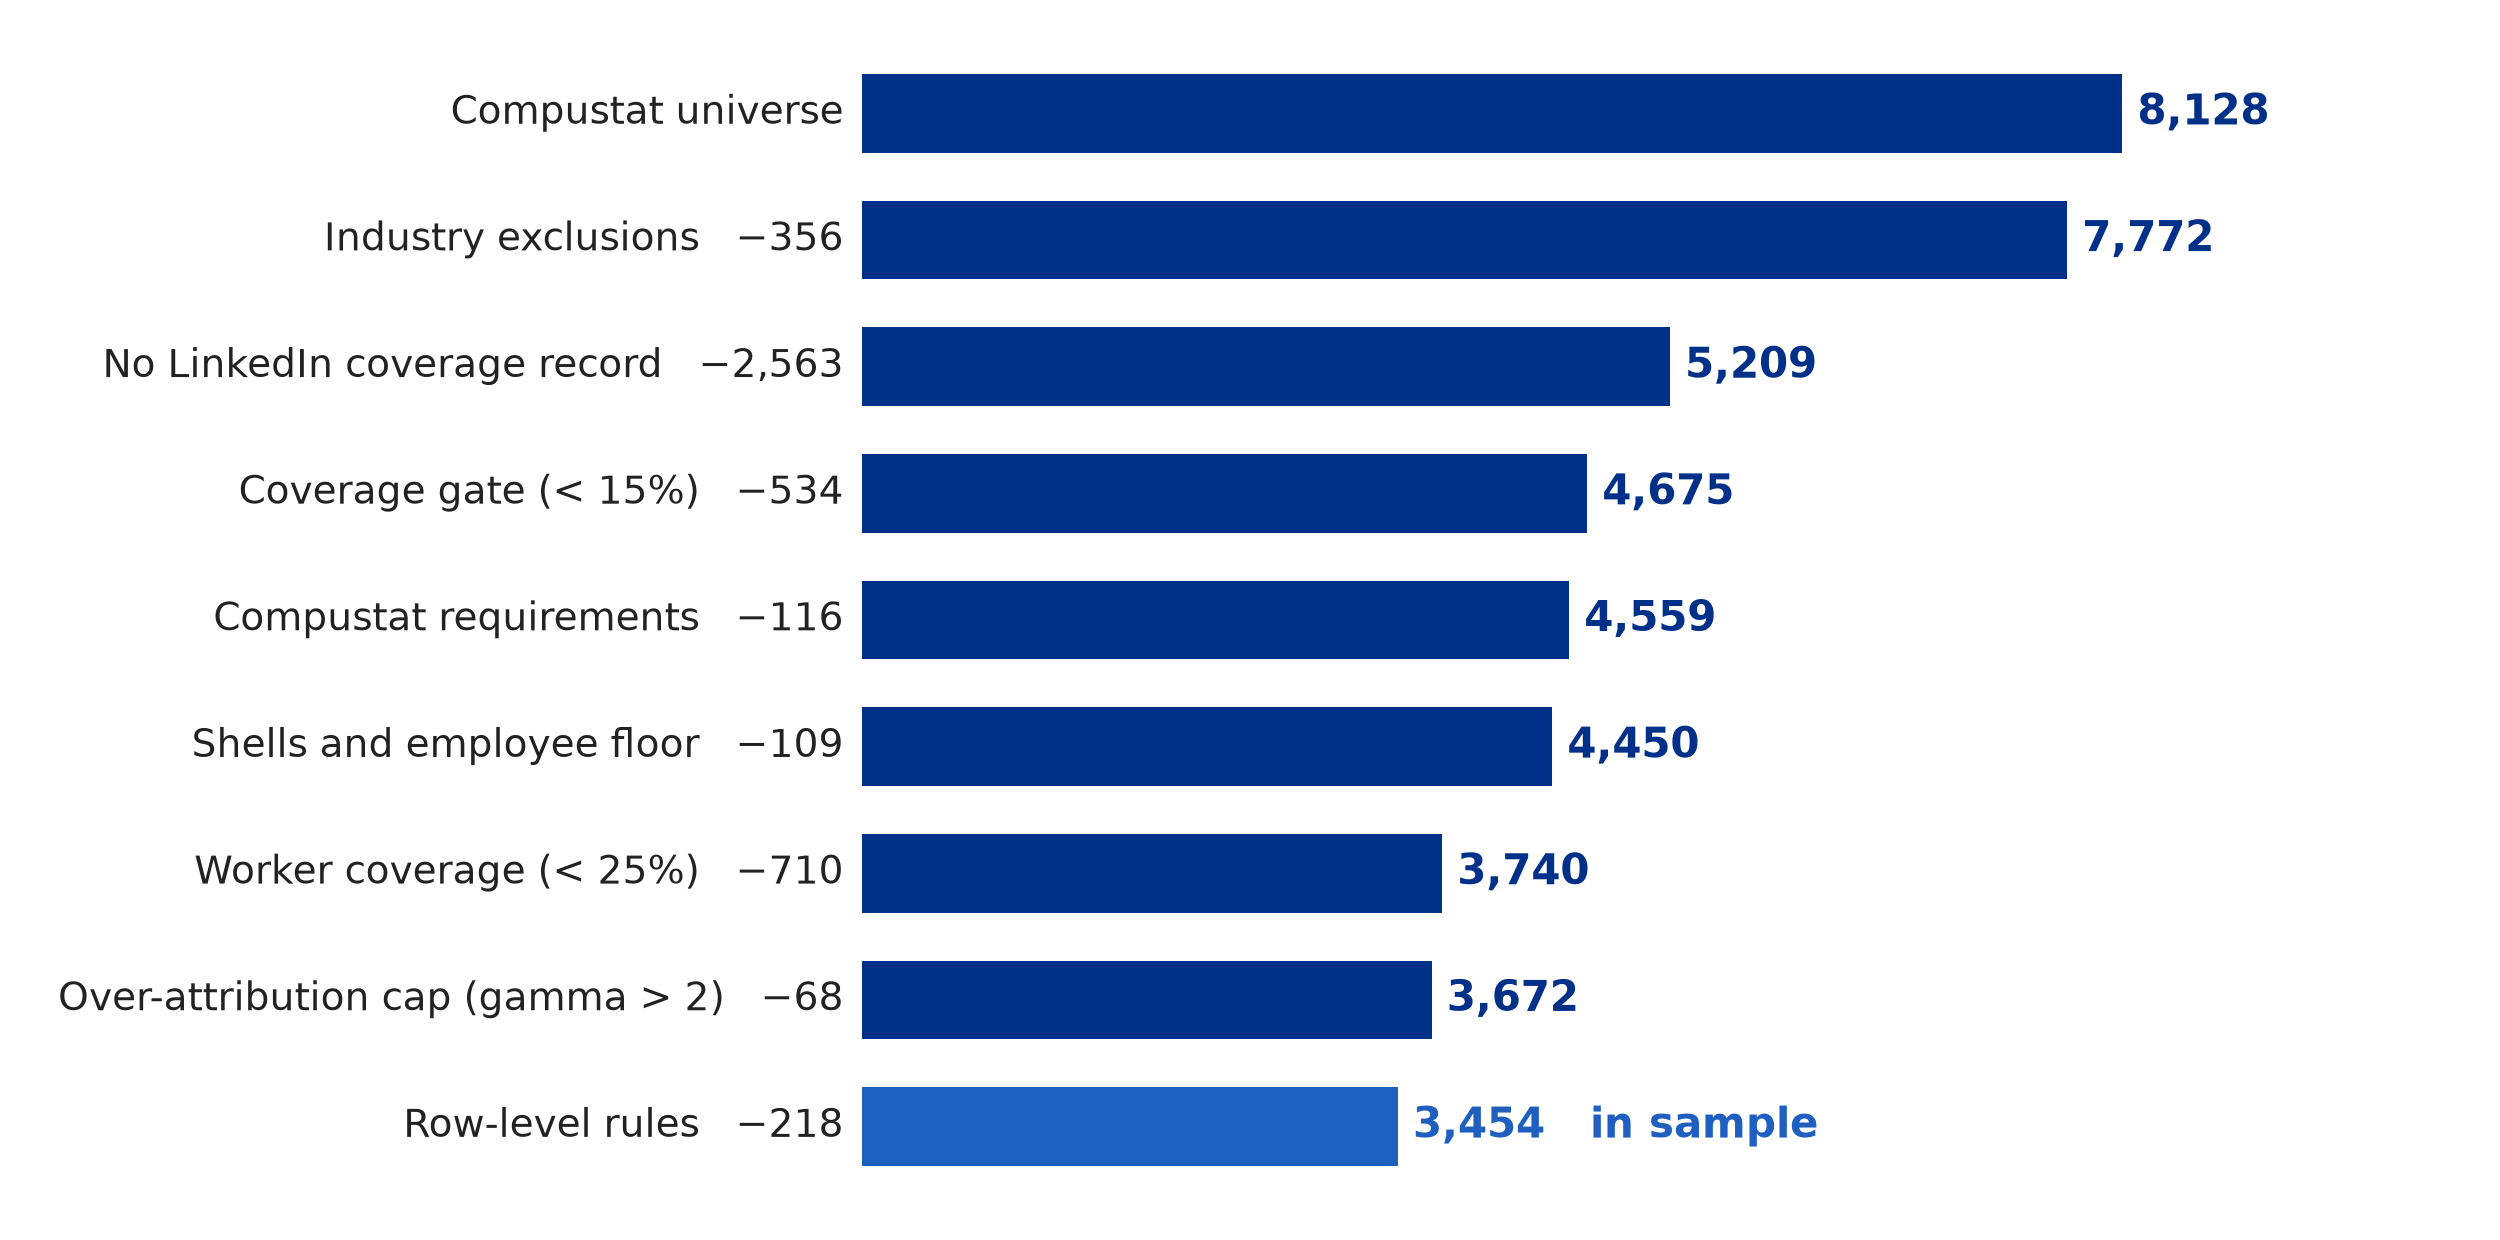
  • Universe: 8,128 matched firms
  • Gates: industry exclusions; LinkedIn/Compustat coverage ≥ 15%; largest-ILM worker share ≥ 25%; Compustat requirements; shells/employee floor; γ>2 cap
  • Final sample: 3,454 firms / 26,112 firm-years, fiscal years 2015–2024; panels 2013–2024
Columbia Business School
Corporate Hierarchy

Merge LinkedIn to Compustat (and more)

  • Compustat: baseline firms
  • Execucomp: fills missing CEOs and top management
  • CRSP (stock prices)
  • BoardEx (boards)
  • DISCERN/KPSS (patents)
  • SDC (mergers)
  • AI use (Babina et al. 2024)
Columbia Business School
Corporate Hierarchy

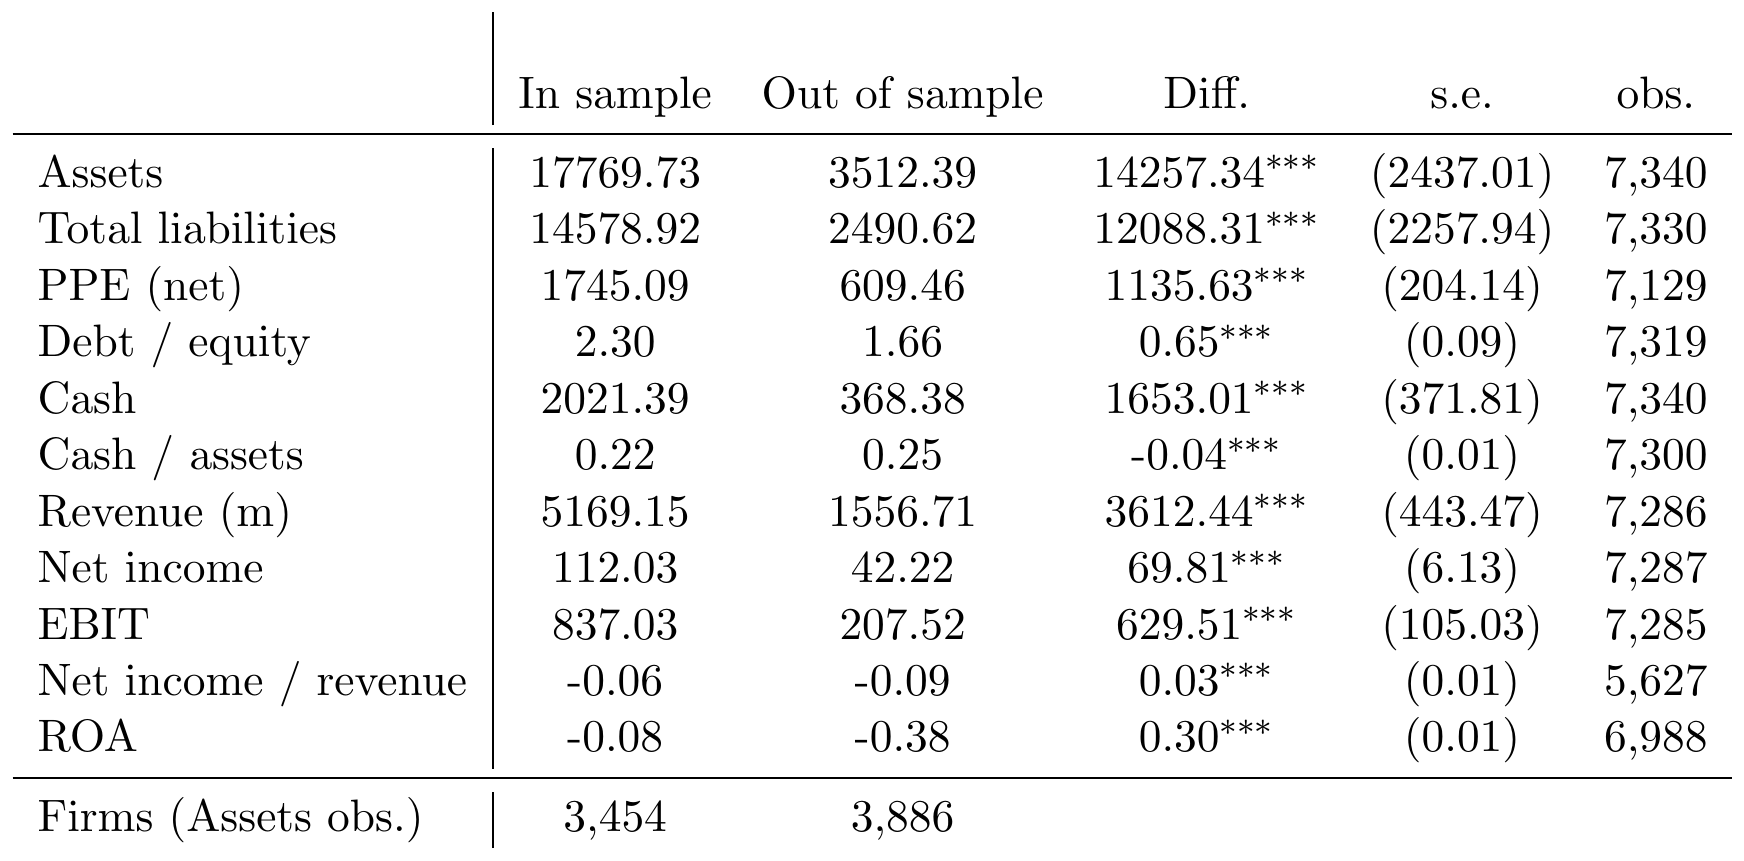
In and out of sample differences

  • In-sample firms are larger, more levered, higher-level profits (directions unchanged)
Columbia Business School
Corporate Hierarchy

Summary statistics

Mean SD Min Median Max N
Number of ILMs (incl. single-role titles) 103.76 85.10 1.00 83.00 710.00 3,454
Number of ILMs (excl. single-role titles) 8.36 4.08 1.00 8.00 34.00 3,454
Size of largest ILM (roles) 190.53 316.58 1.00 91.00 3900.00 3,454
Number of unique roles 304.14 392.41 2.00 188.00 4623.00 3,454
% role in largest ILM 55.00 20.35 3.77 58.82 100.00 3,454
% worker-years in largest ILM 77.27 20.47 25.00 85.04 100.00 3,454
Employees (Compustat, 1000s) 7.99 37.41 0.00 0.98 1556.00 3,406
Number employees (LinkedIn, '000s) 3.23 11.37 0.00 0.64 325.56 3,454
Number hierarchy layers (selected) 6.35 2.14 2.00 6.00 18.00 3,454
Hierarchization (German) 0.60 0.10 0.00 0.62 1.00 1,091
Hierarchization (ONet) 0.51 0.12 0.00 0.52 0.76 3,454
Hierarchization (this paper) 0.77 0.10 0.14 0.79 0.91 3,326
Algorithm rules
Not all employees
Columbia Business School
Corporate Hierarchy

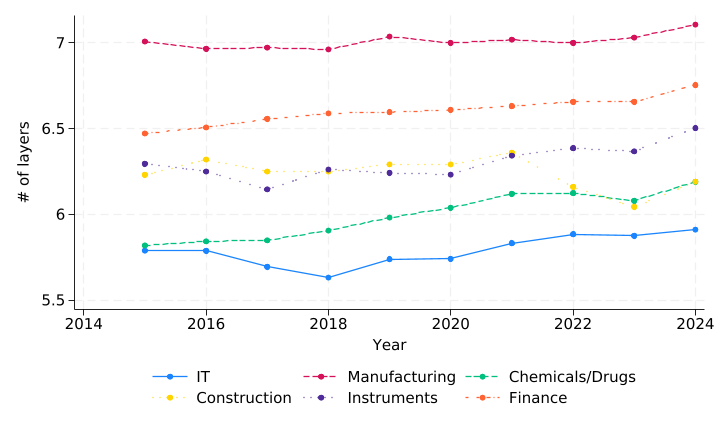
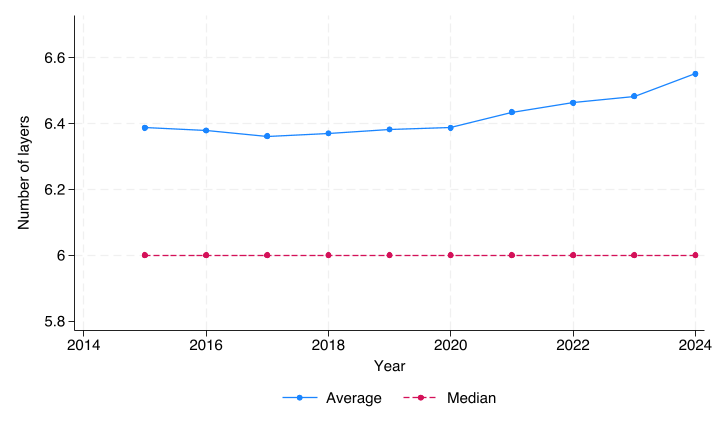
Layers over time: flat to weakly increasing

  • Mean 6.39 (2015) → 6.55 (2024); median 6 throughout
  • 19% of firms ever change their layer count
Columbia Business School
Corporate Hierarchy

But doesn’t LinkedIn suck?

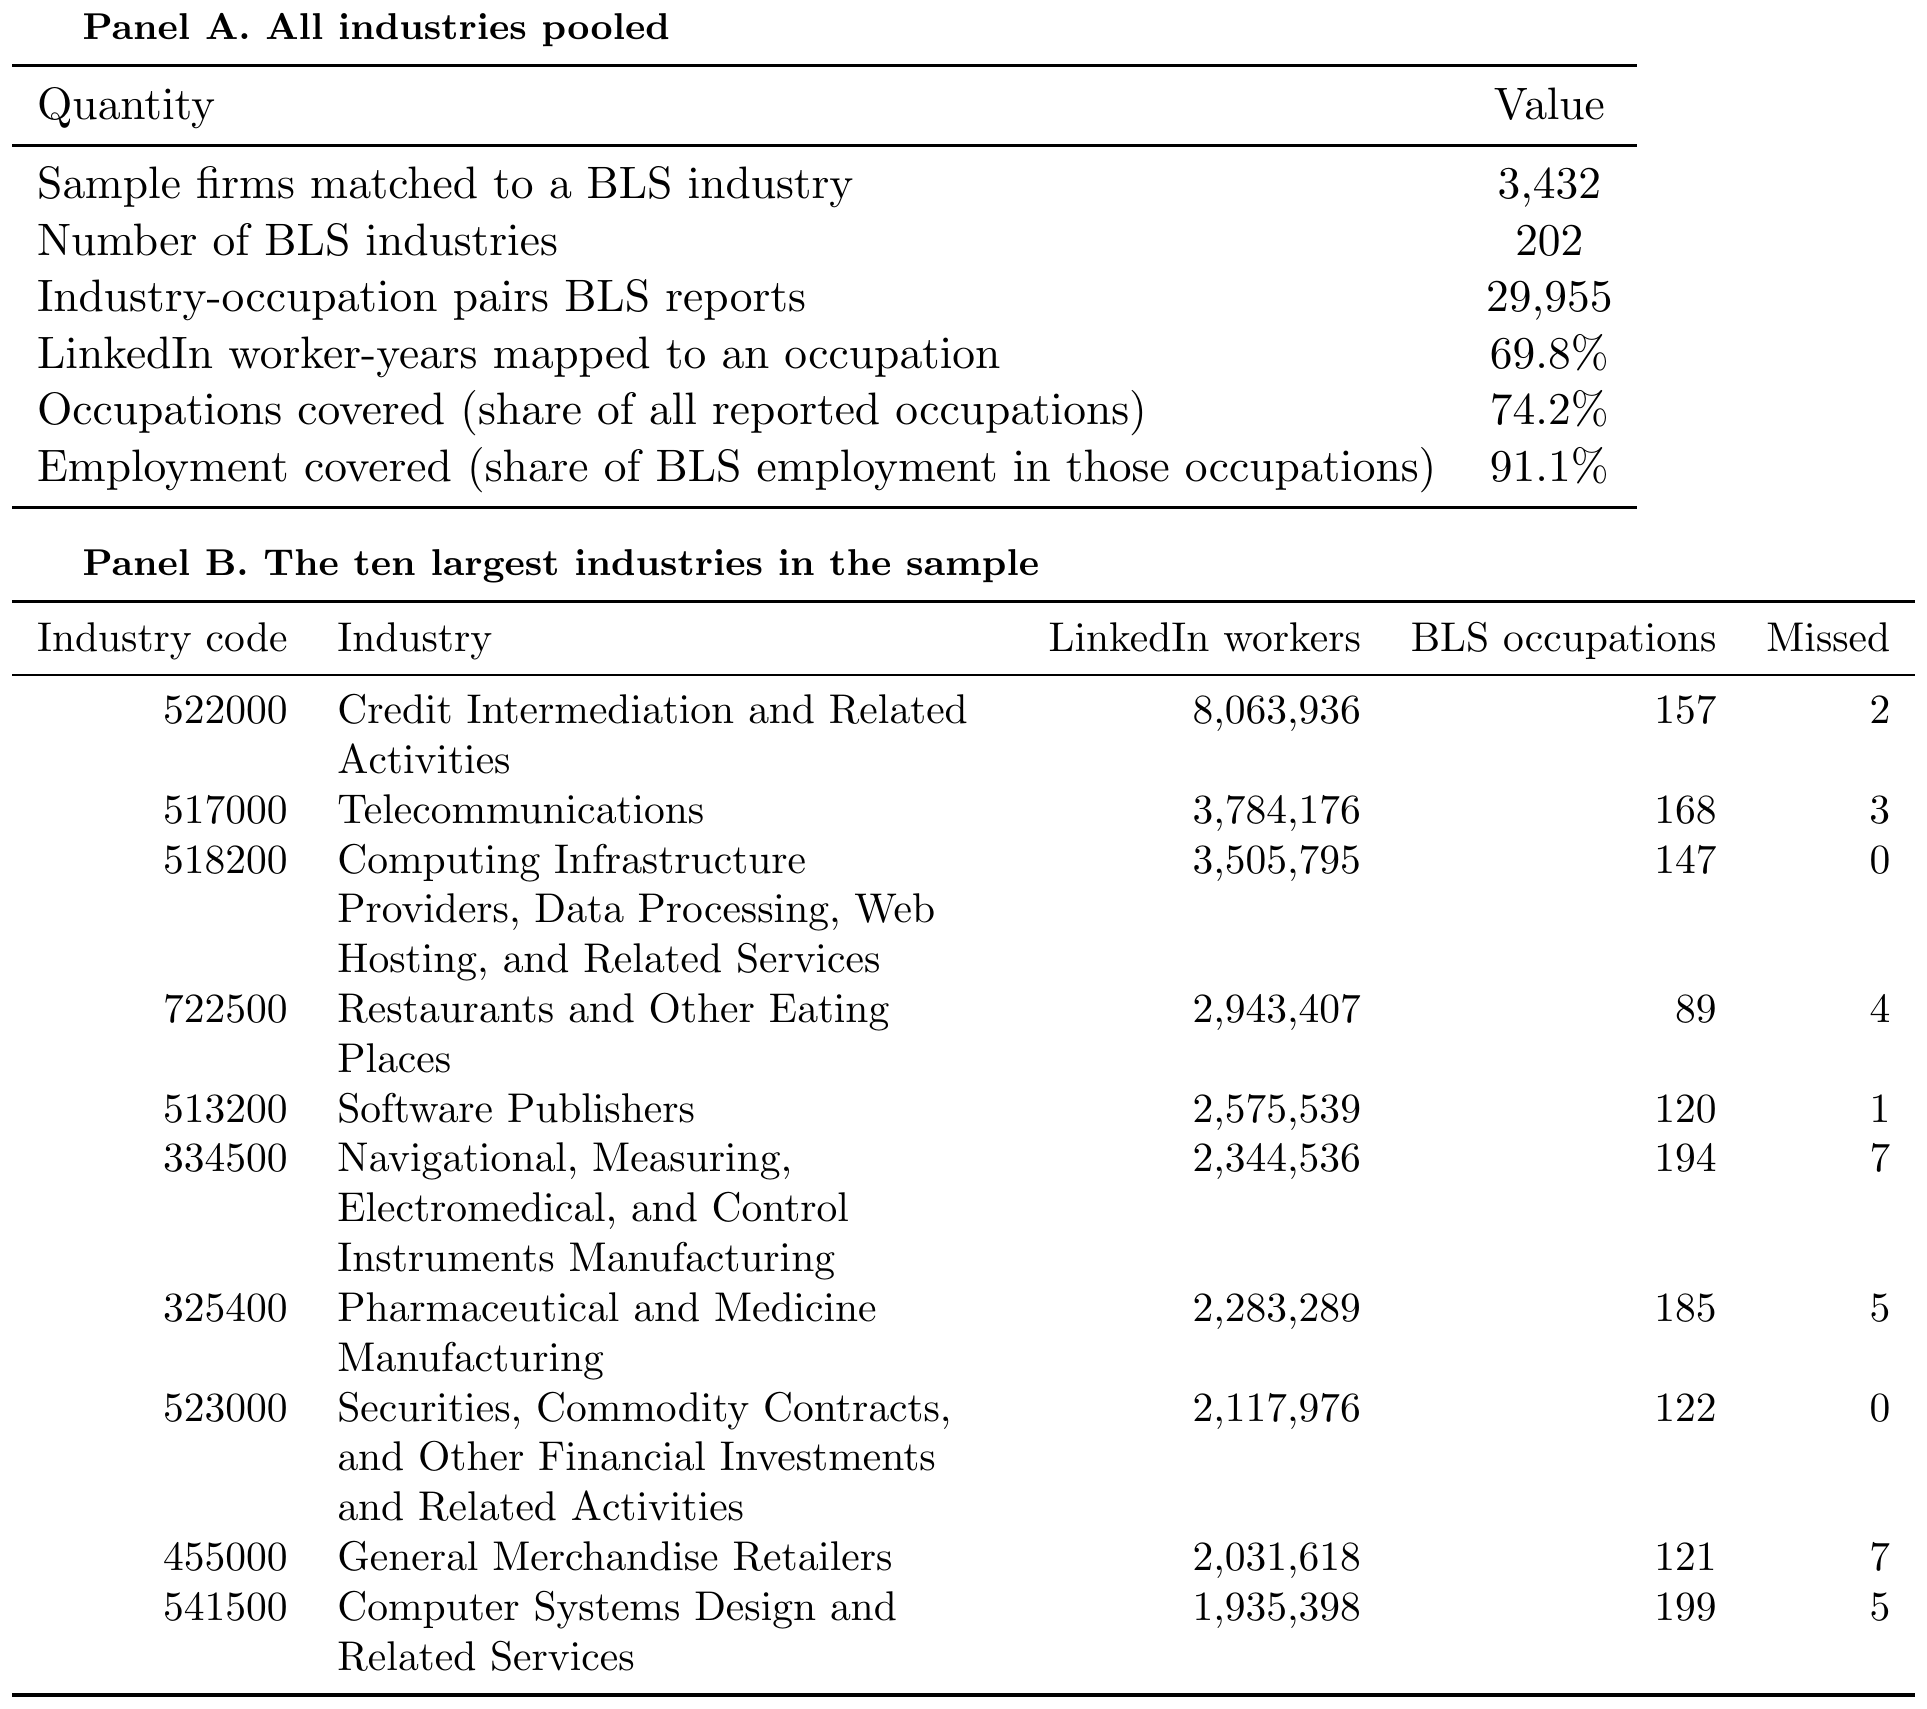
  • Yes: LinkedIn does not have every title BLS benchmark: LinkedIn sees 74.2% of the occupations reported for the firm’s industry
  • Yes: it does not cover every employee Median firm: LinkedIn headcount is 68% of the Compustat headcount
  • What this paper needs:
    • A representative set of roles on the main job ladder
    • An understanding of where LinkedIn is missing or unrepresentative, and whether that biases the estimated hierarchy
Columbia Business School
Corporate Hierarchy

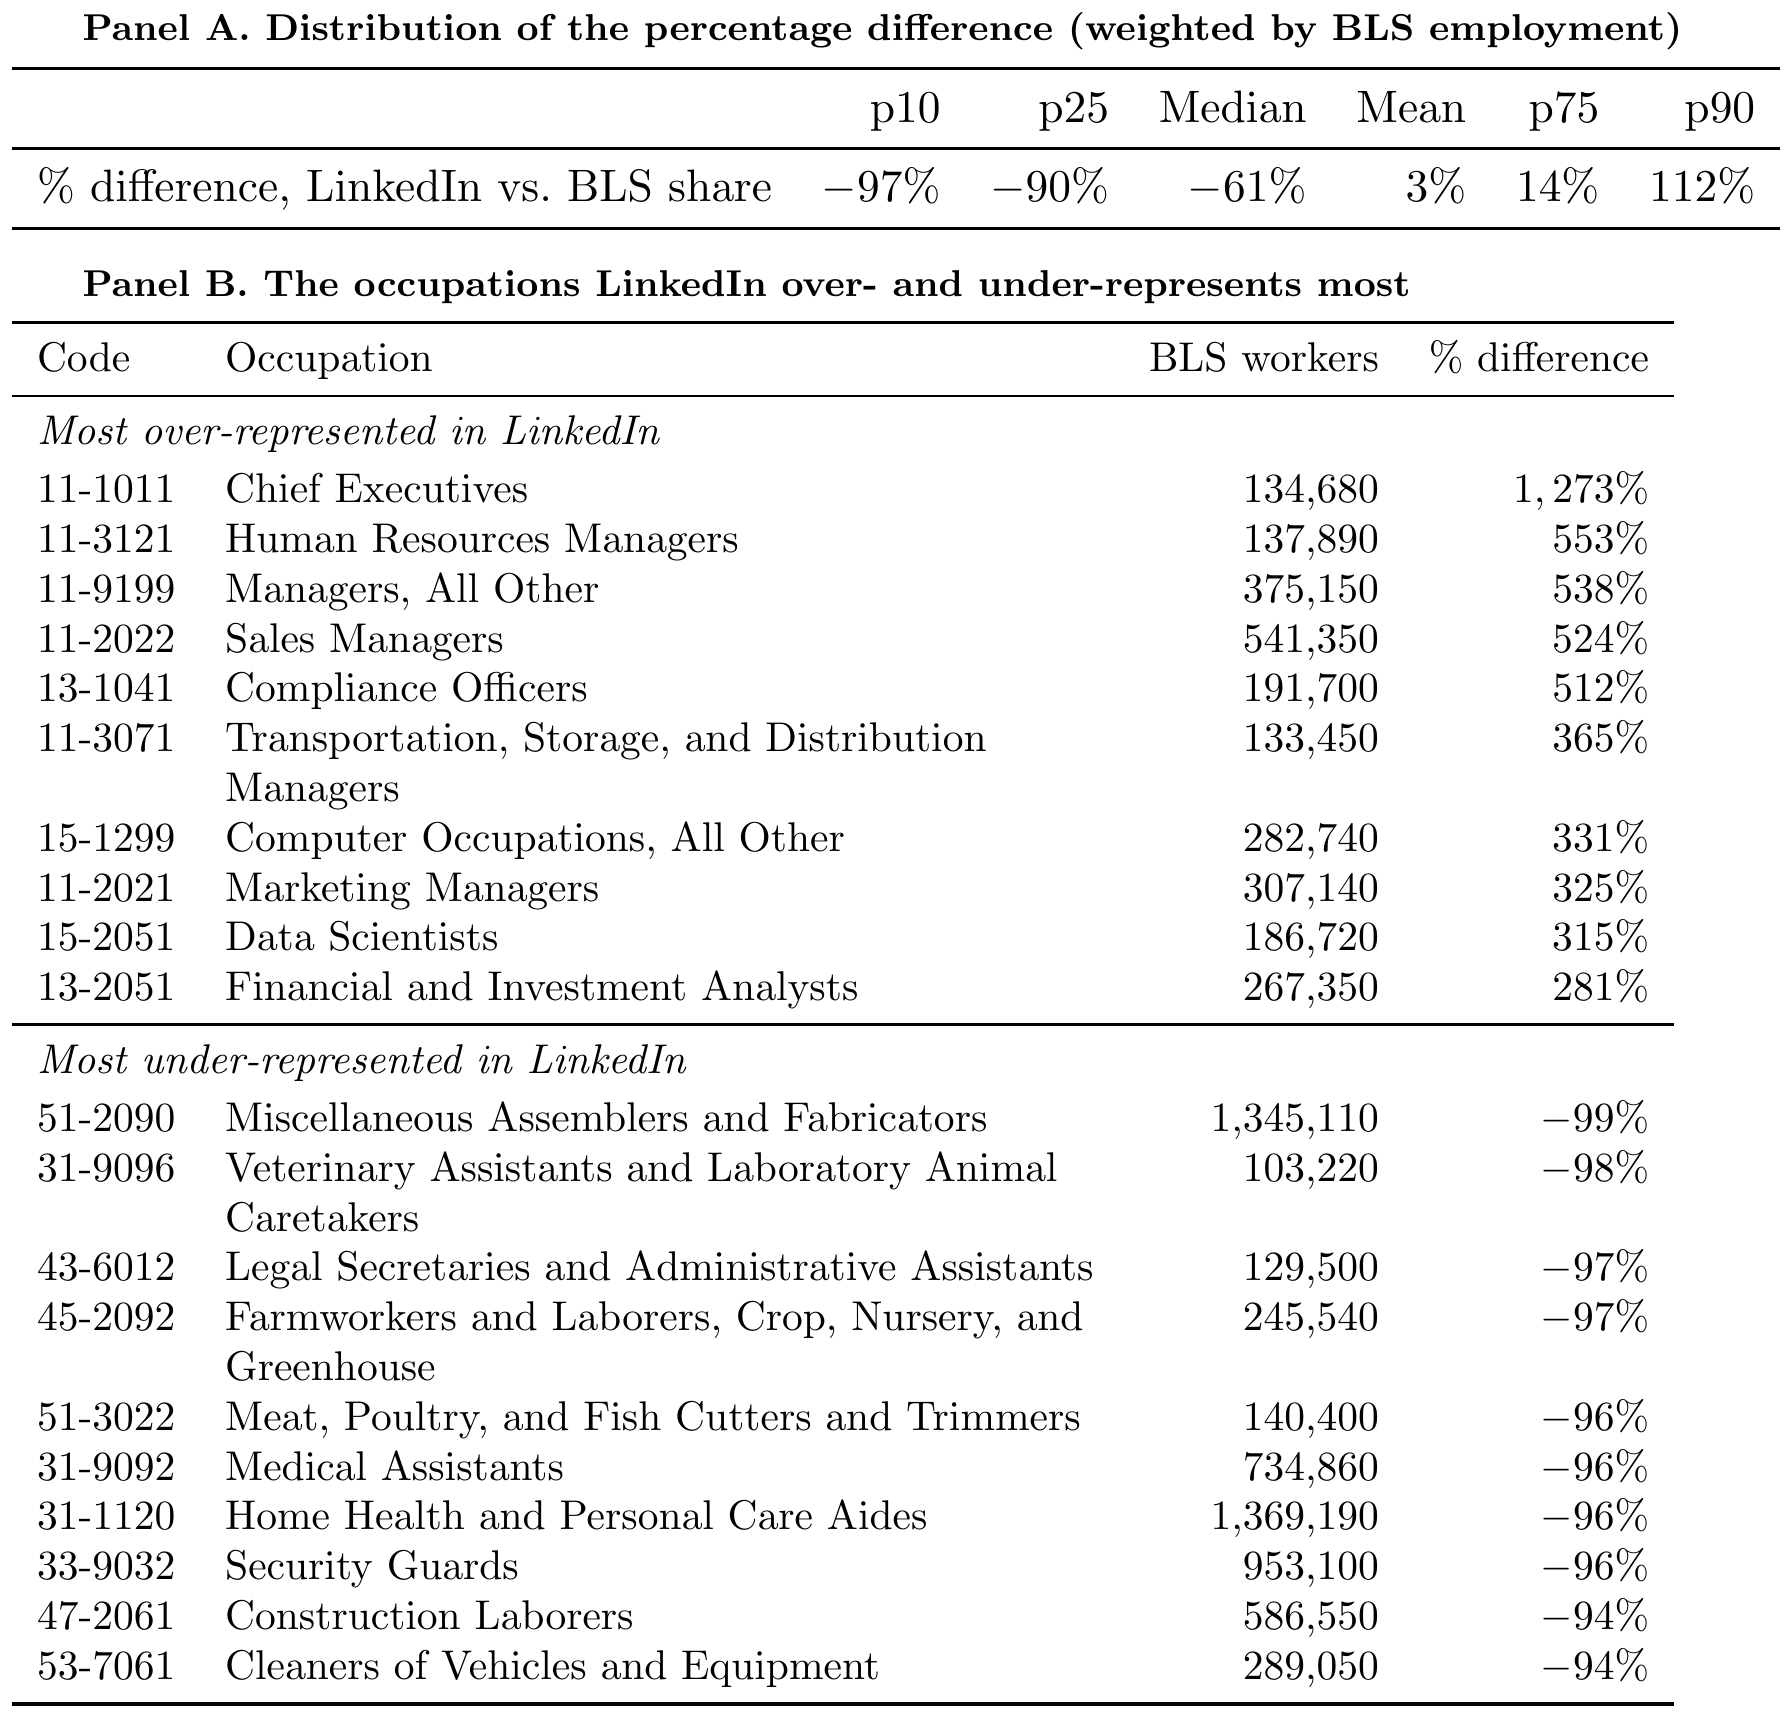
Benchmarking LinkedIn against the BLS

  • BLS: employment by occupation within each industry (OEWS, May 2024)
  • LinkedIn titles mapped to BLS occupations through O*NET; 69.8% of worker-years matched

Coverage

LinkedIn sees 74.2% of the occupations the BLS reports, covering 91.1% of their employment

Missing occupations

Mid-pay nationally, but near the bottom of pay inside our firms; mostly off the main job ladder or in its middle

Mix

Managers and executives overrepresented (a recruiting platform); aides, guards, assemblers, laborers underrepresented

Bias

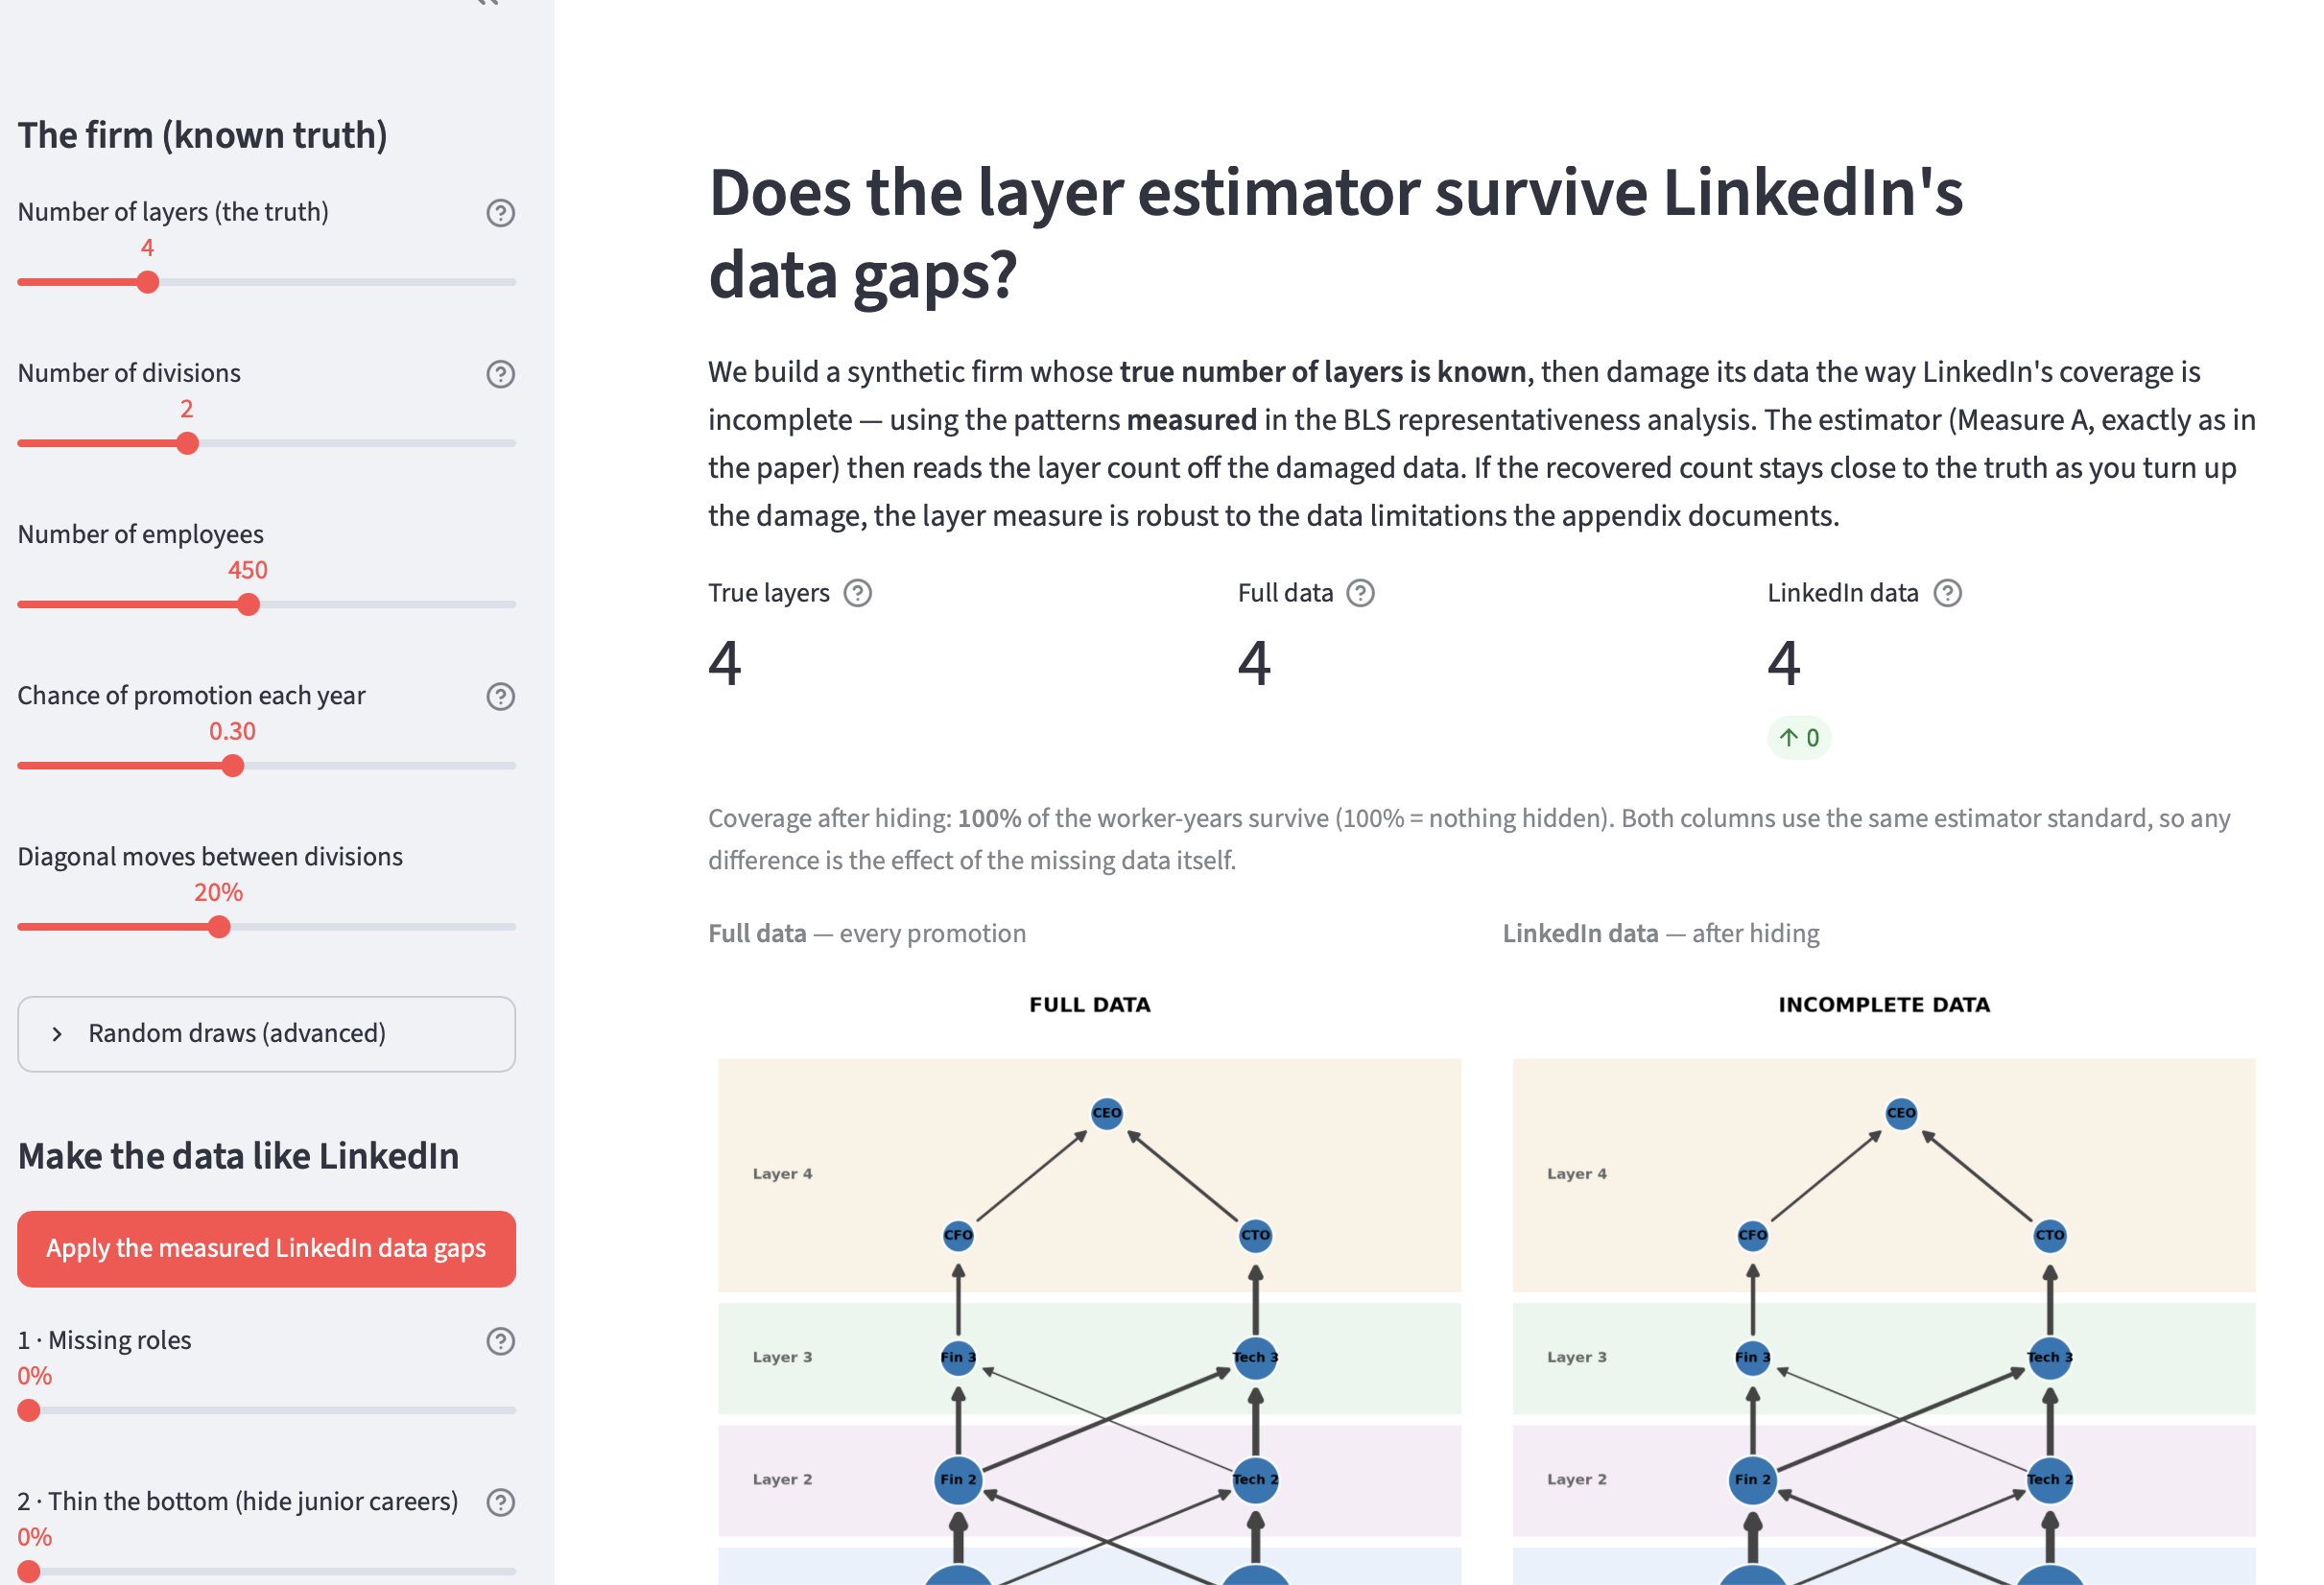
With 16% of roles removed and 68% of headcount kept, the estimator recovers the true layer count in 99.5% of simulated firms; otherwise off by one

Try the simulator: hierarchy-coverage-sim.onrender.com

Columbia Business School
Corporate Hierarchy
Validation
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

What should a measure look like?

  • intuitive titles and roles in hierarchical layers
  • higher layers → more experience
  • strongly correlates with firm size
  • firms should be (roughly) pyramidal in shape
  • where there are layers, there should be managers
Columbia Business School
Corporate Hierarchy

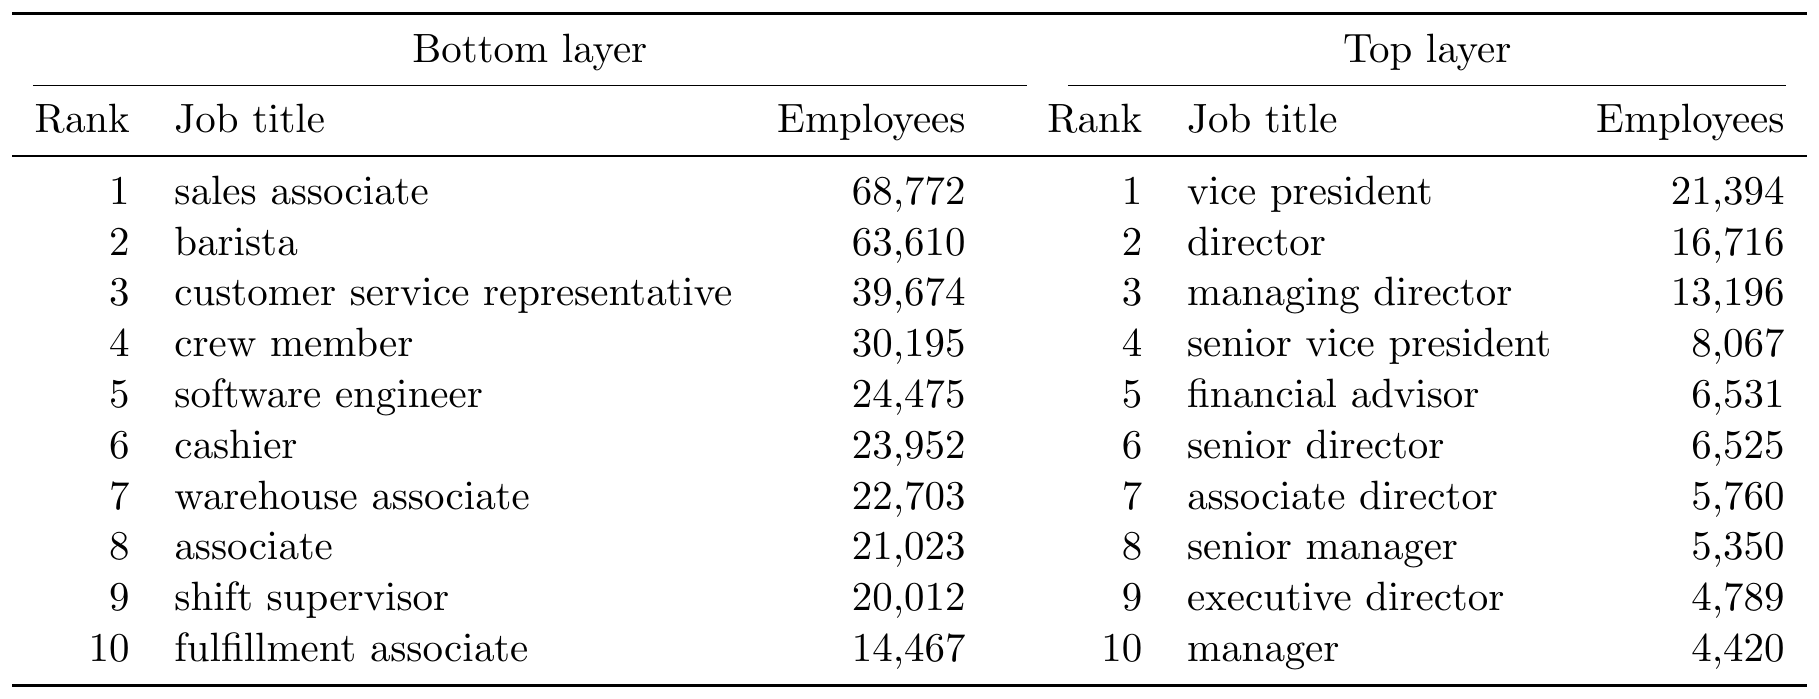
Titles by layer match expectations
Columbia Business School
Corporate Hierarchy

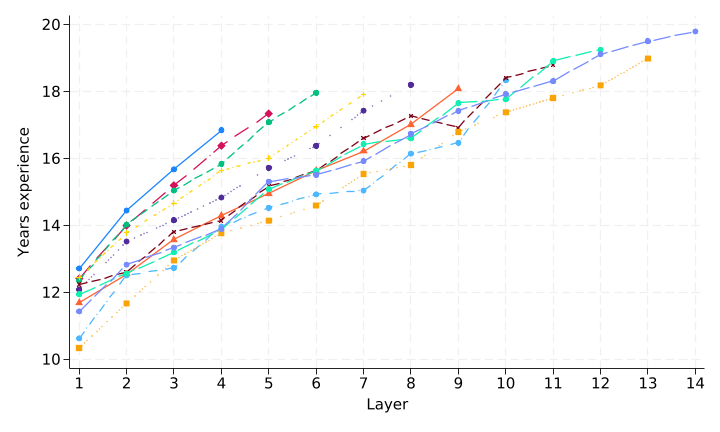
Experience rises with layer

  • Experience = years since first job or BA
Columbia Business School
Corporate Hierarchy

Firm size predicts layers
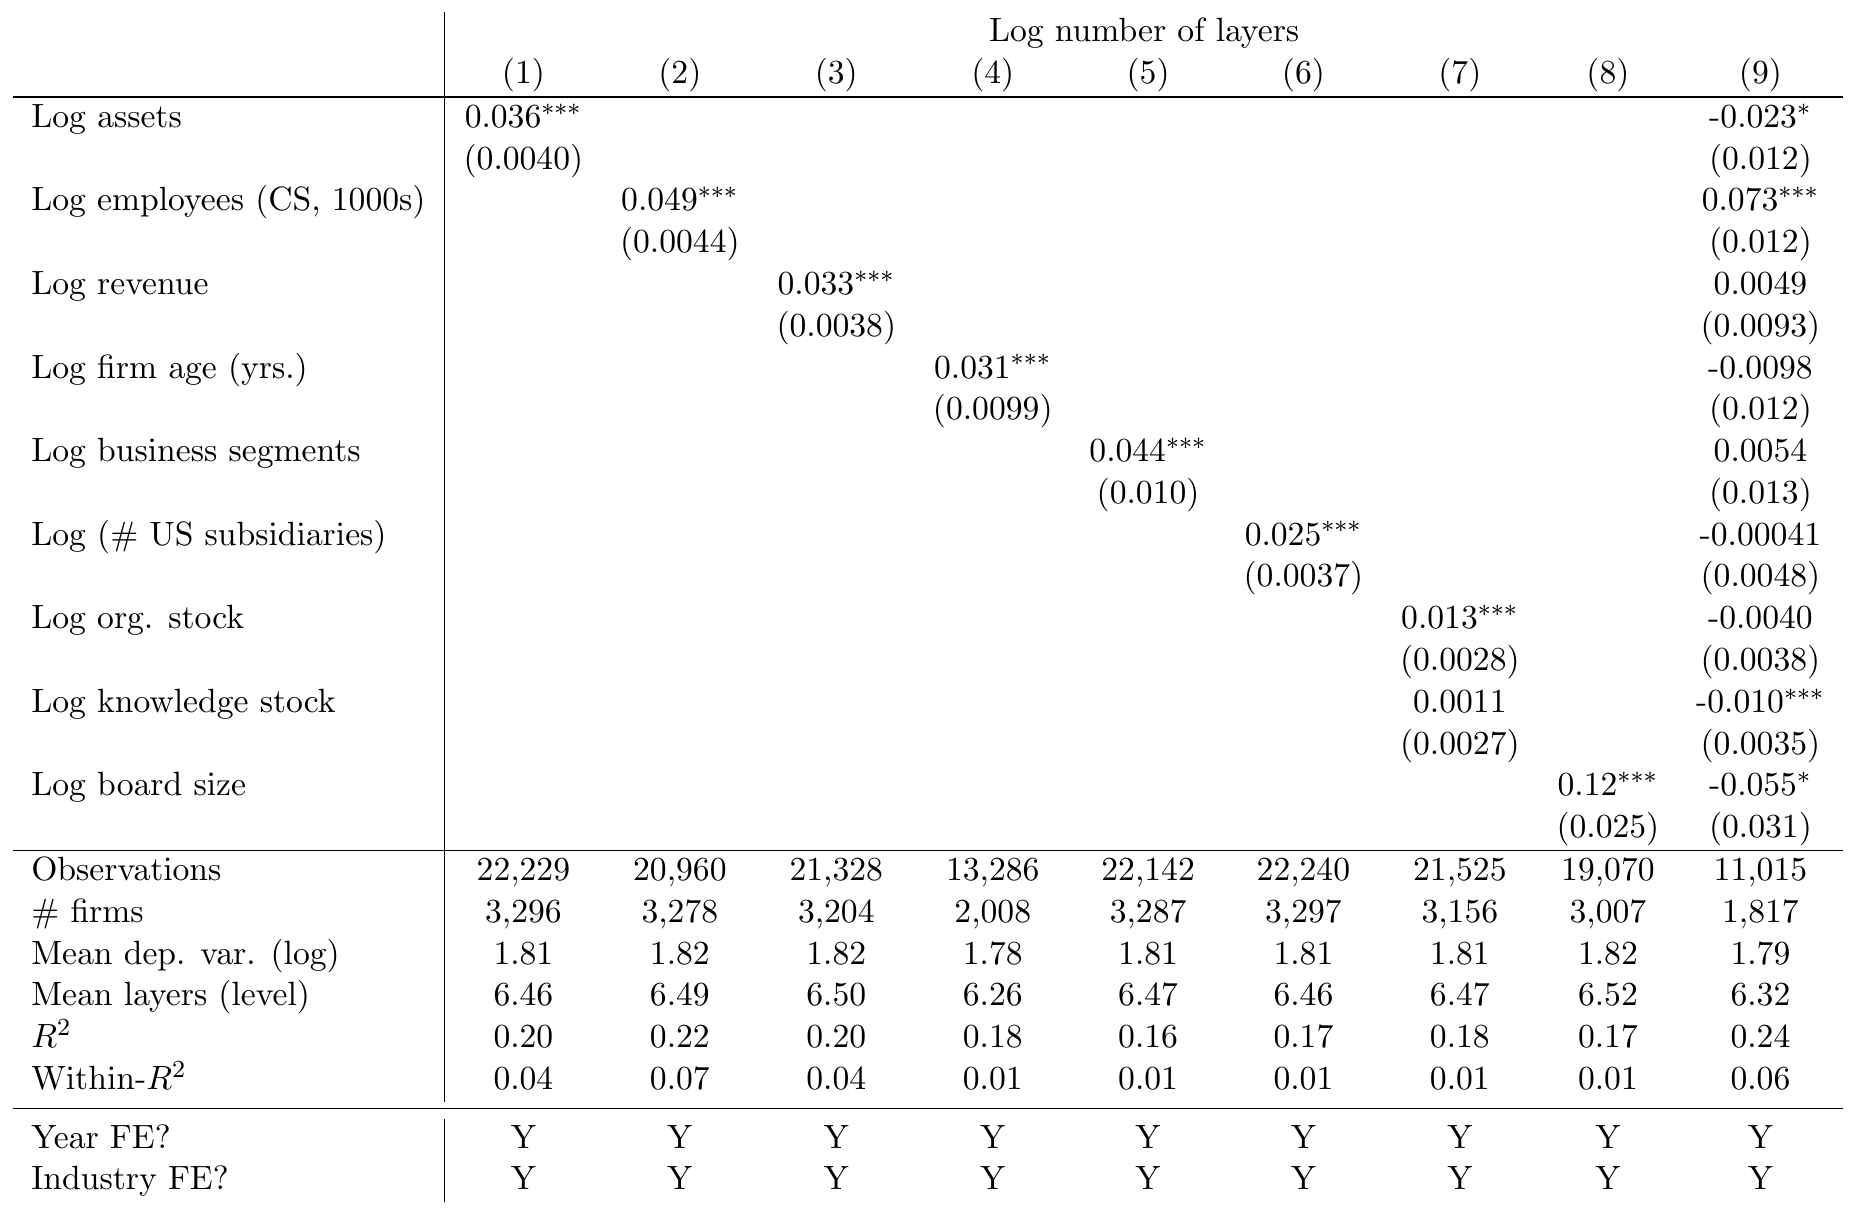
Columbia Business School
Corporate Hierarchy

Typical firm has a pyramidal shape
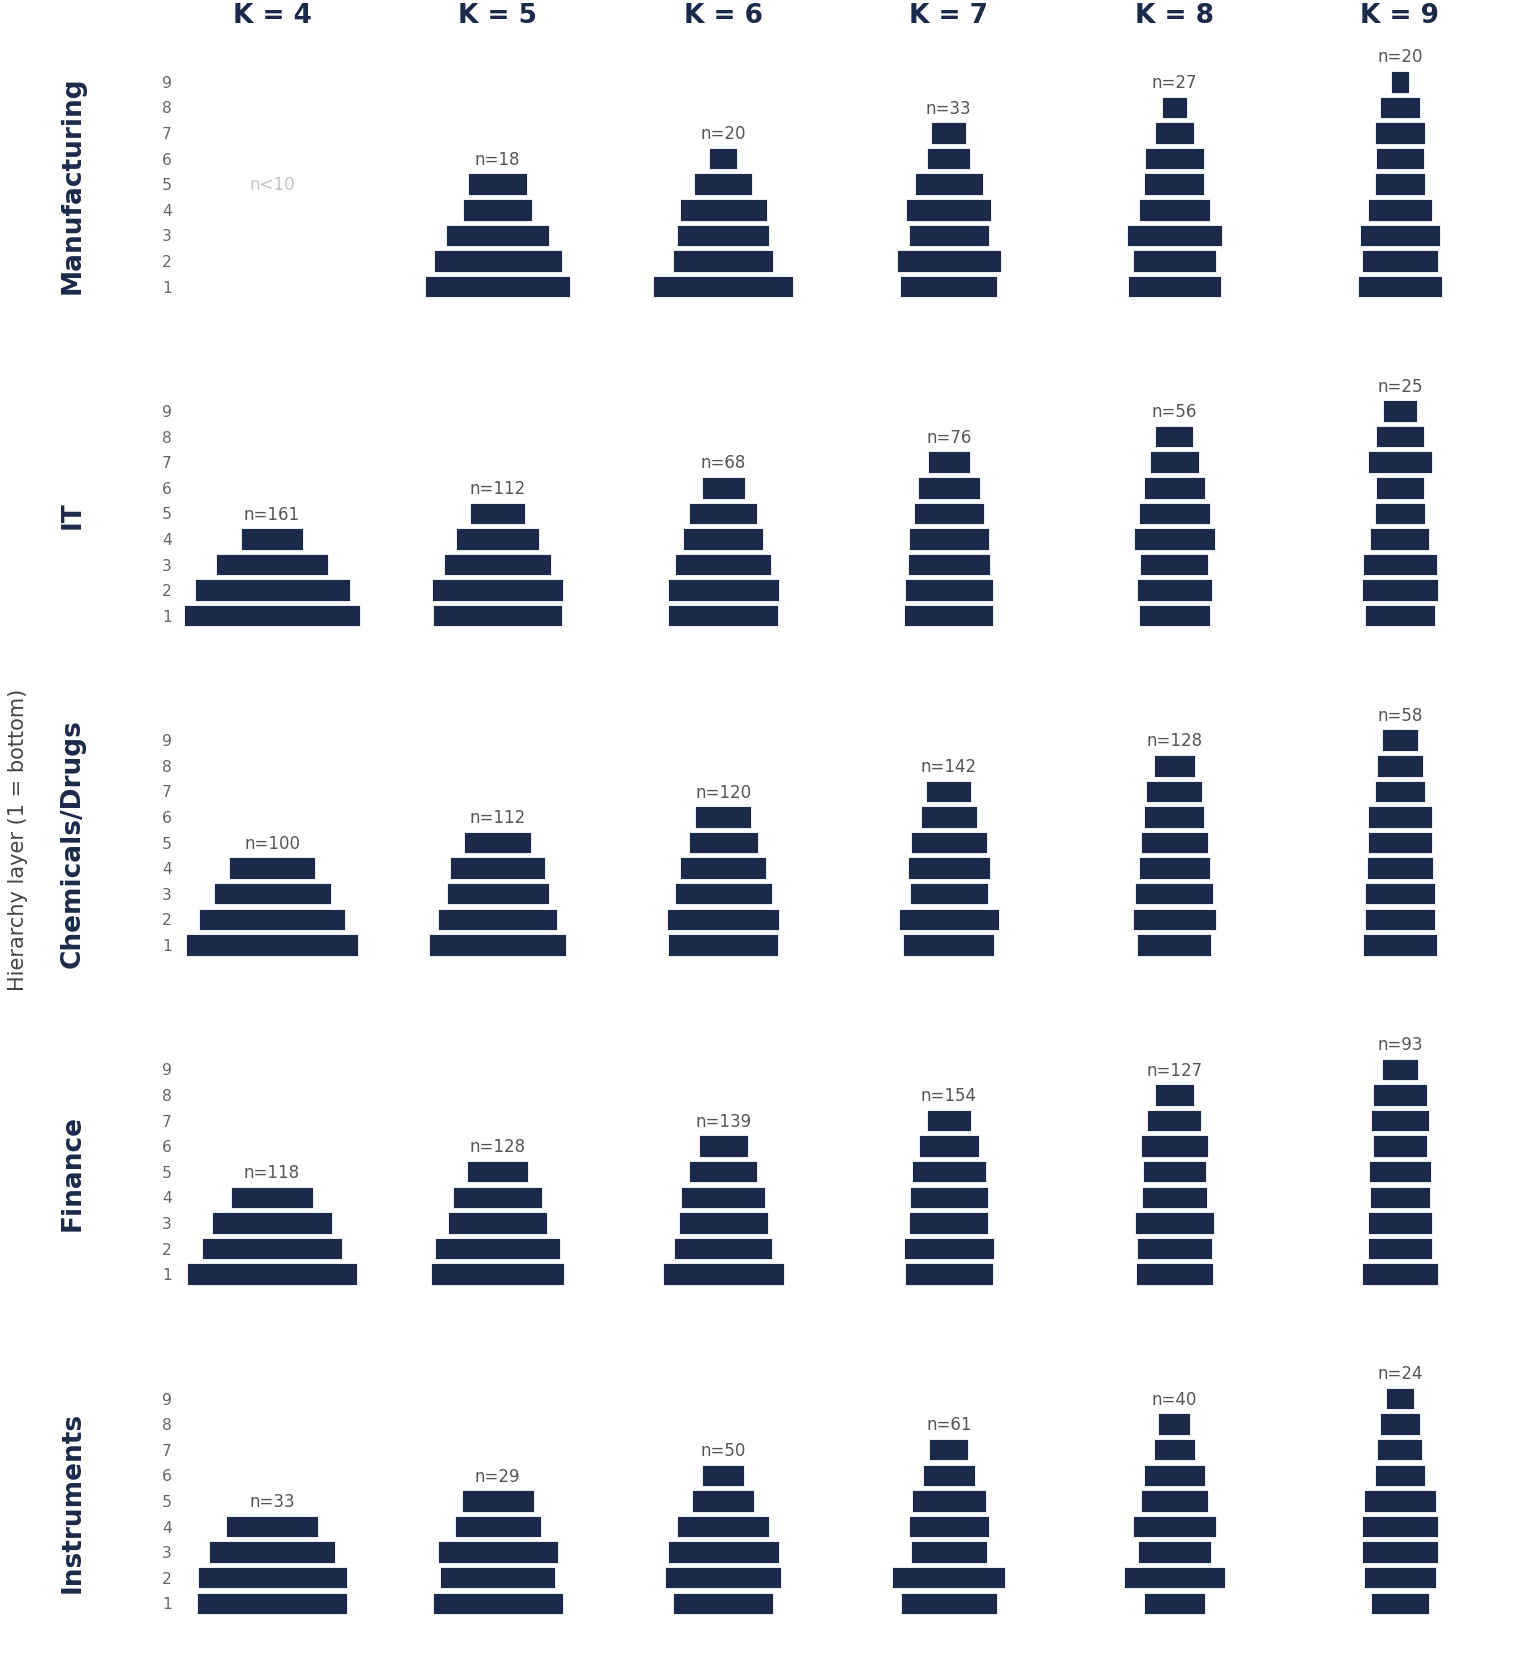
Columbia Business School
Corporate Hierarchy

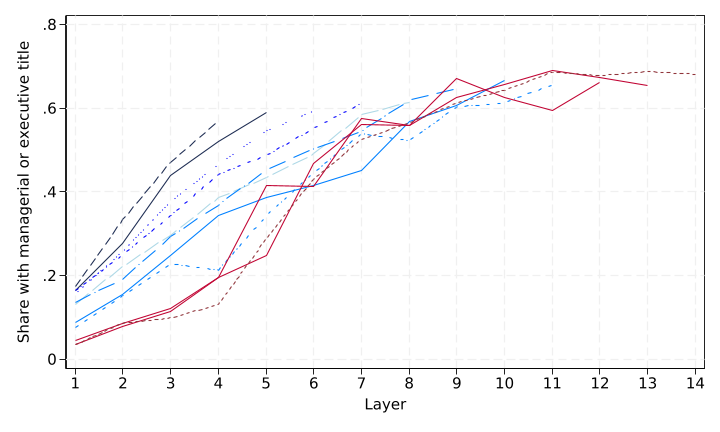
Managerial and executive titles by layer

  • Share of workers with a managerial or executive title rises up the hierarchy, flattening only at the top of the highest-layer firms
  • Each line: firms with the same number of layers
  • Consistent with knowledge hierarchy theory
Columbia Business School
Corporate Hierarchy

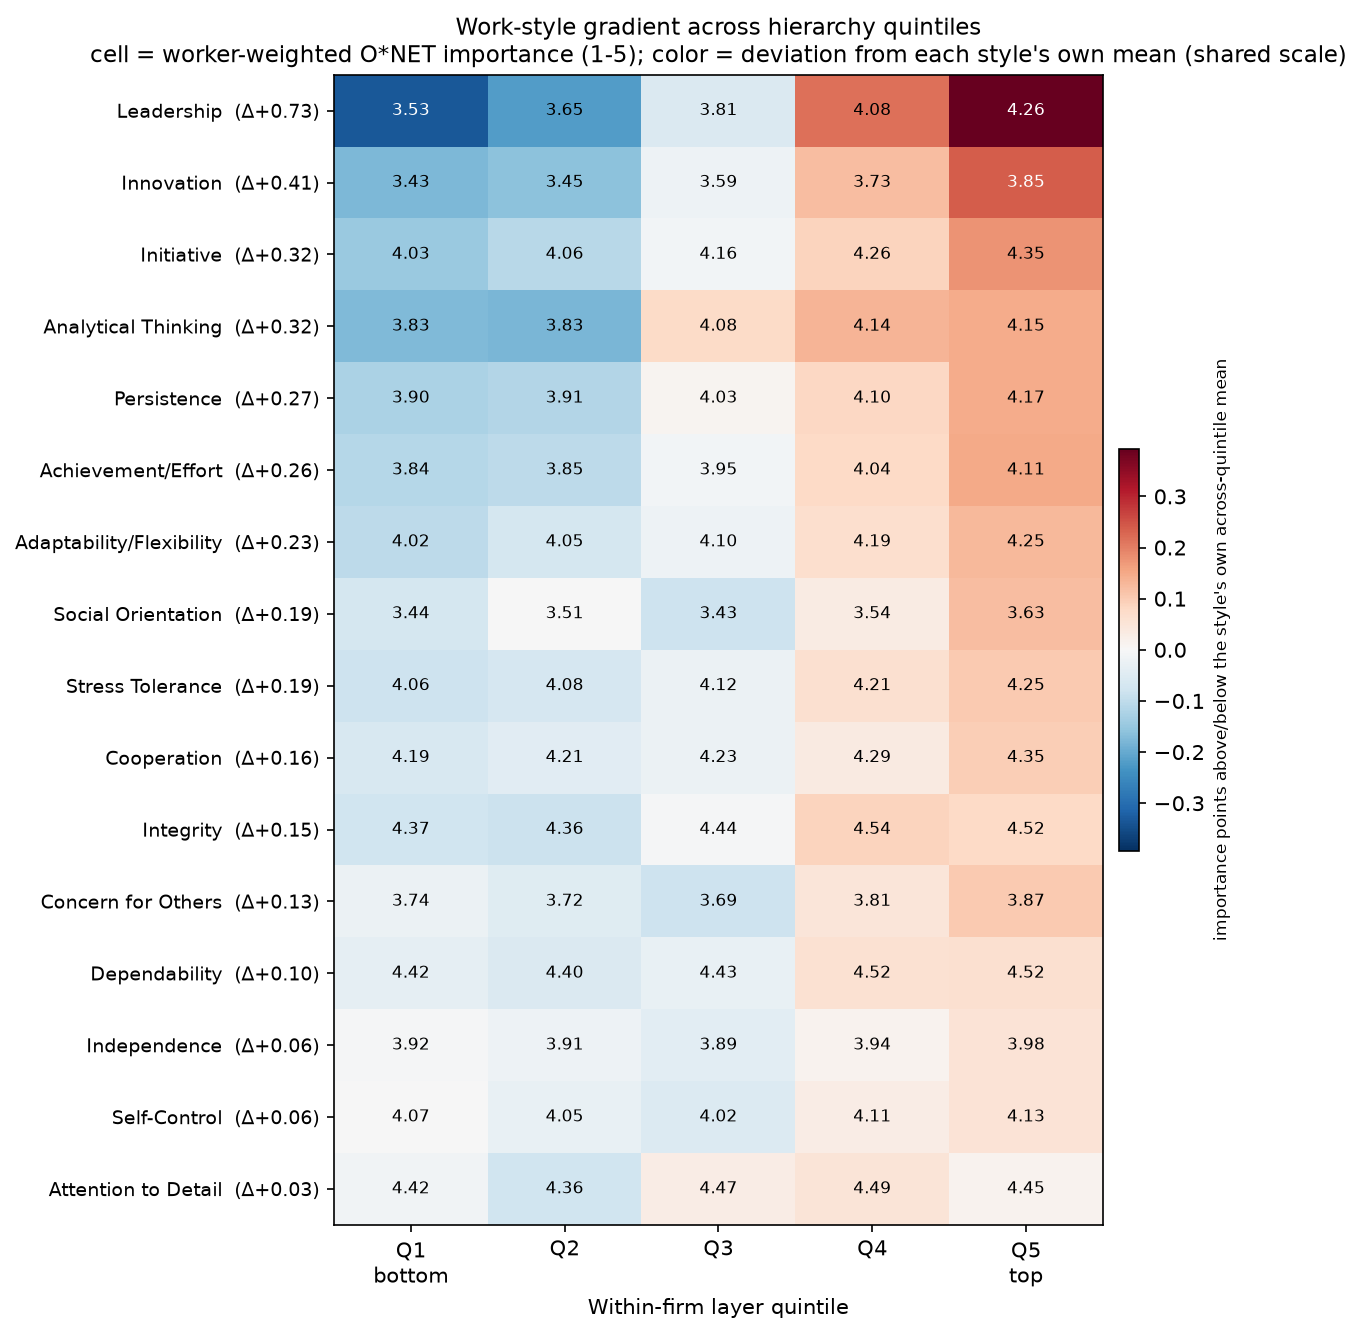
External gradients: wages, work styles, skill

  • BLS wages: top rank quintile pays about twice the bottom
  • O*NET work styles: leadership, innovation, initiative rise up the hierarchy
  • O*NET Job Zone: top quintile sits more than a full zone above the bottom
Columbia Business School
Corporate Hierarchy

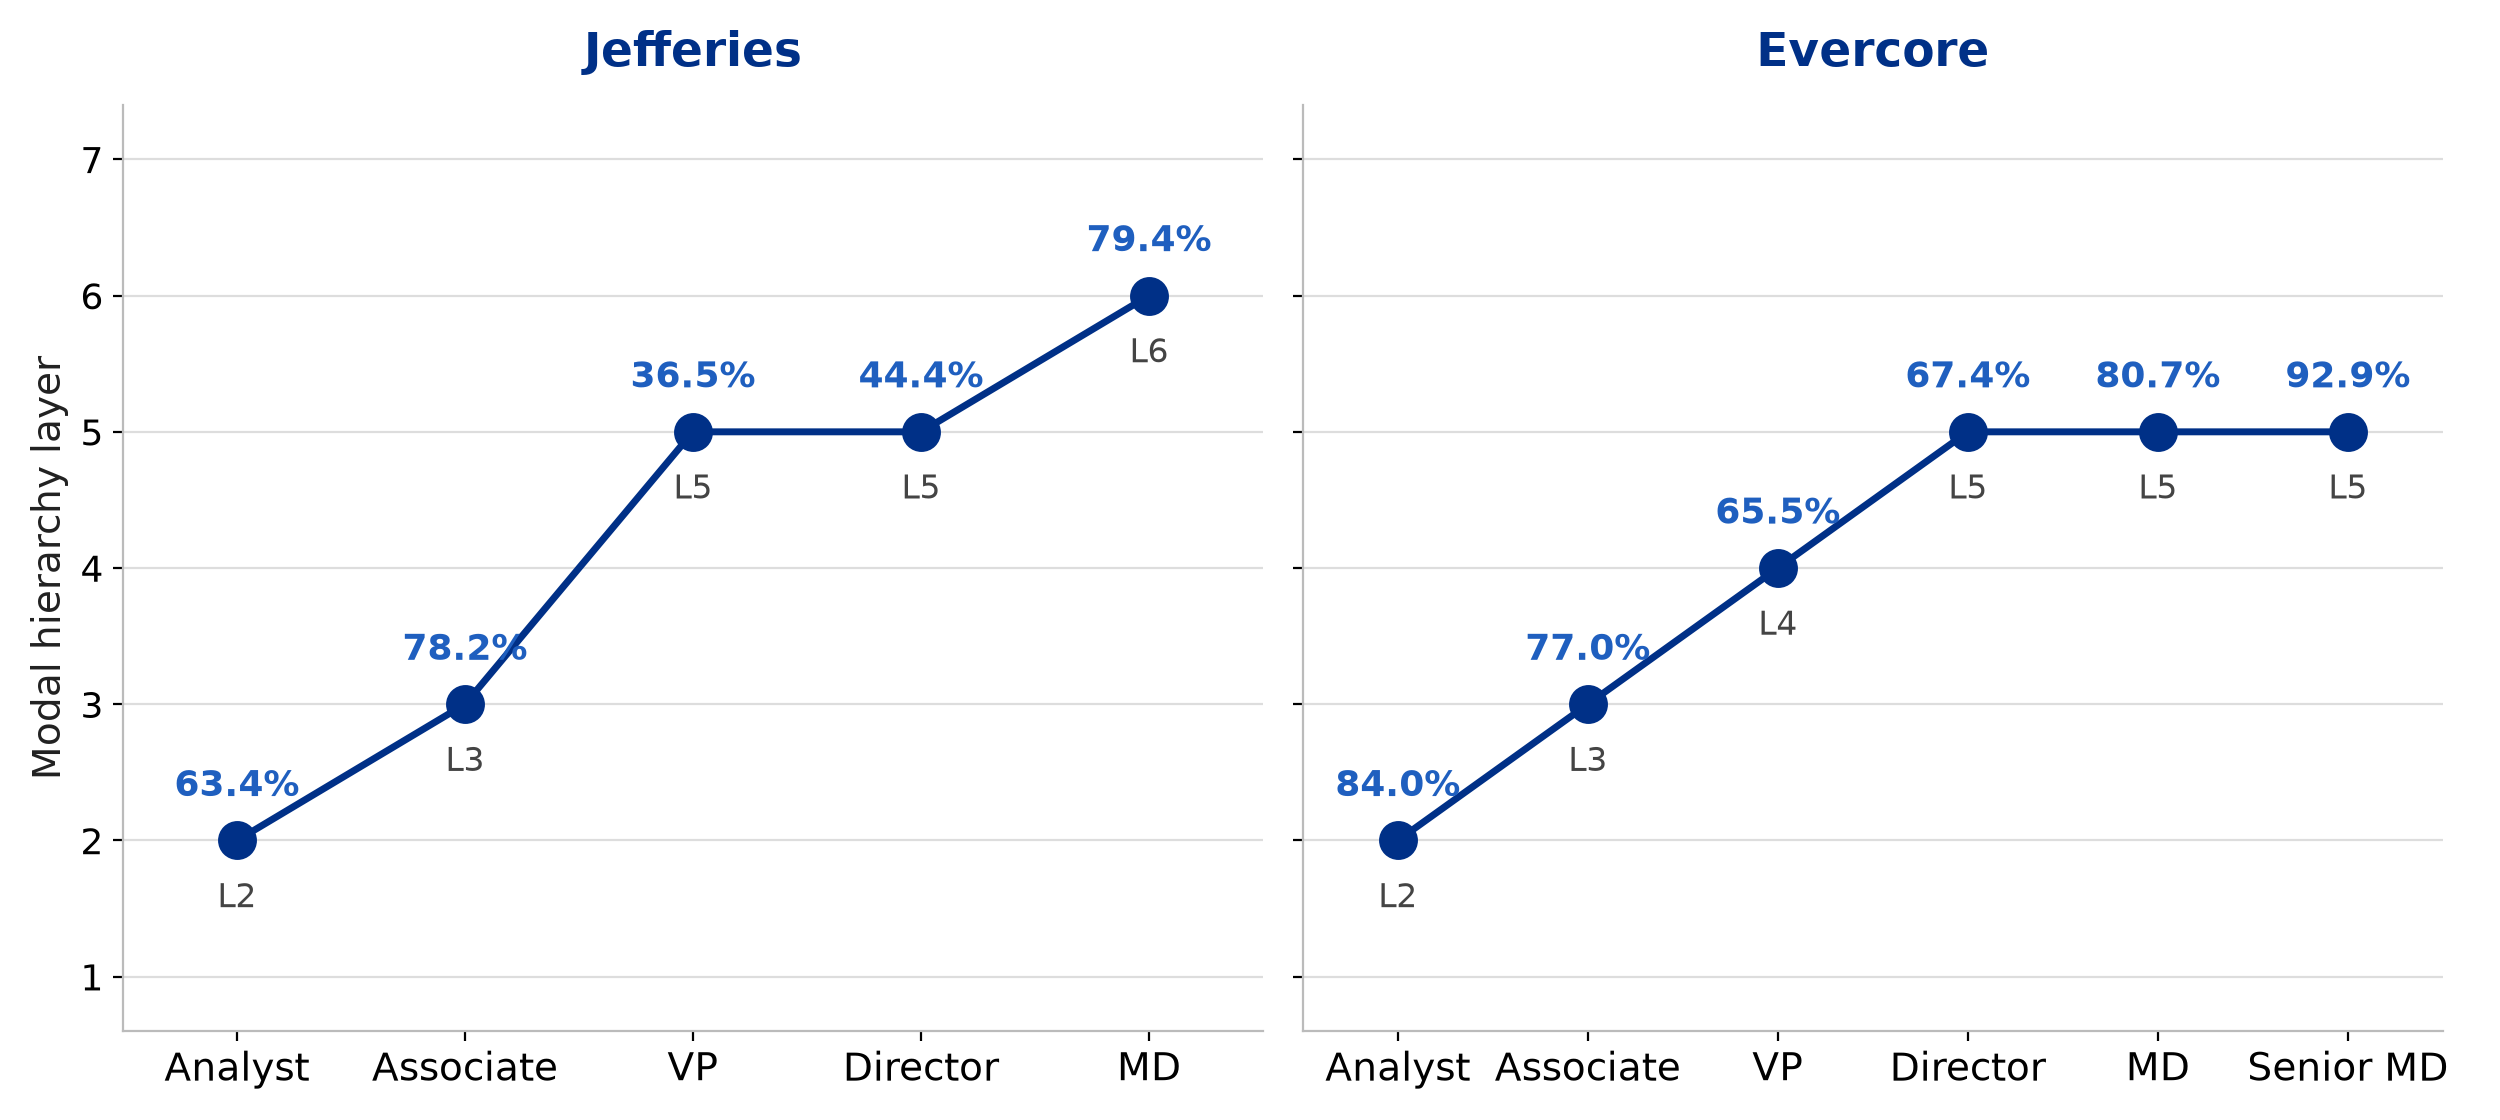
Known job ladders: investment banks

  • Jefferies: 7 layers; analyst → associate → VP → MD land on rising layers (modal layers 2/3/5/6)
  • Evercore: 7 layers; same weakly increasing ladder (2/3/4/5)
  • Lazard not in sample
Columbia Business School
Corporate Hierarchy
Outcomes
Does hierarchy predict firm decisions and outcomes?
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

Questions we ask

  • Are more hierarchical firm’s human capital different?
  • Does hierarchy correlate with firm productivity and costs?
  • Can we explain firm investment in innovation?
  • Do stock volatility and resilience to shocks depend on layers?
Columbia Business School
Corporate Hierarchy
What follows is not identified
Columbia Business School
Corporate Hierarchy

Human capital: education

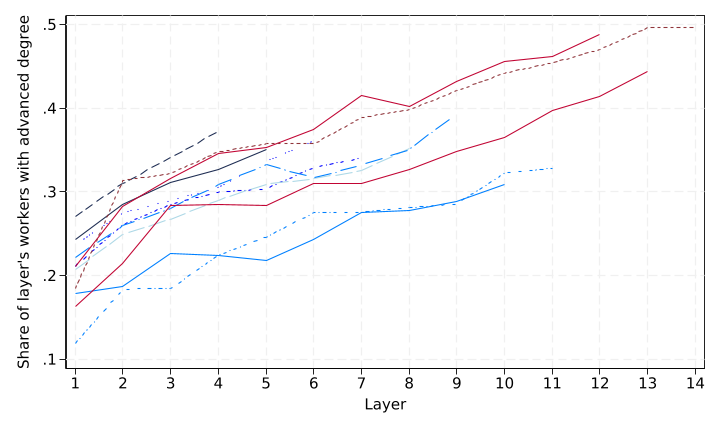
  • The share of workers with a post-graduate degree rises with the layer
  • Consistent with theory: additional layers require costly-to-acquire managerial knowledge (Rosen 1982; Garicano 2000)
Columbia Business School
Corporate Hierarchy

Human capital: tenure and turnover

  • The question: does the internal labor market of high-layer firms differ?
  • High-layer firms hire internally at higher rates and their workers have longer tenure
  • Consistent with firm-specific human capital
Employees Tenure (log years)
% new % promote Non-new All
layer
(1) (2) (3) (4)
log # layers (t−1) -0.0080** 0.0069*** 0.057*** 0.073***
(0.0036) (0.0016) (0.022) (0.026)
Observations 22,257 22,257 22,257 22,257
# firms 3,304 3,304 3,304 3,304
Mean dep. var. 0.17 0.04 1.72 1.52
R² 0.02 0.01 0.07 0.07
Size decile FE? Y Y Y Y
Year FE? Y Y Y Y
Industry FE? Y Y Y Y
Columbia Business School
Corporate Hierarchy

Employee equity and the CEO

  • High-layer firms are more likely to offer employee stock option plans
  • Significantly higher wage inequality (CEO pay ratio): consistent with tournament models and increasingly costly skills at the top
ESOP? Internal CEO CEO
CEO pay pay ratio
(5) (6) (7) (8)
log # layers (t−1) 0.095*** 0.028 0.064 35.0***
(0.024) (0.055) (0.064) (5.77)
Observations 13,533 1,210 11,180 7,266
# firms 2,071 862 1,470 1,861
Mean dep. var. 0.14 0.59 8.60 109.26
R² 0.10 0.01 0.30 0.29
Size decile FE? Y Y Y Y
Year FE? Y Y Y Y
Industry FE? Y Y Y Y
Columbia Business School
Corporate Hierarchy

Operating performance

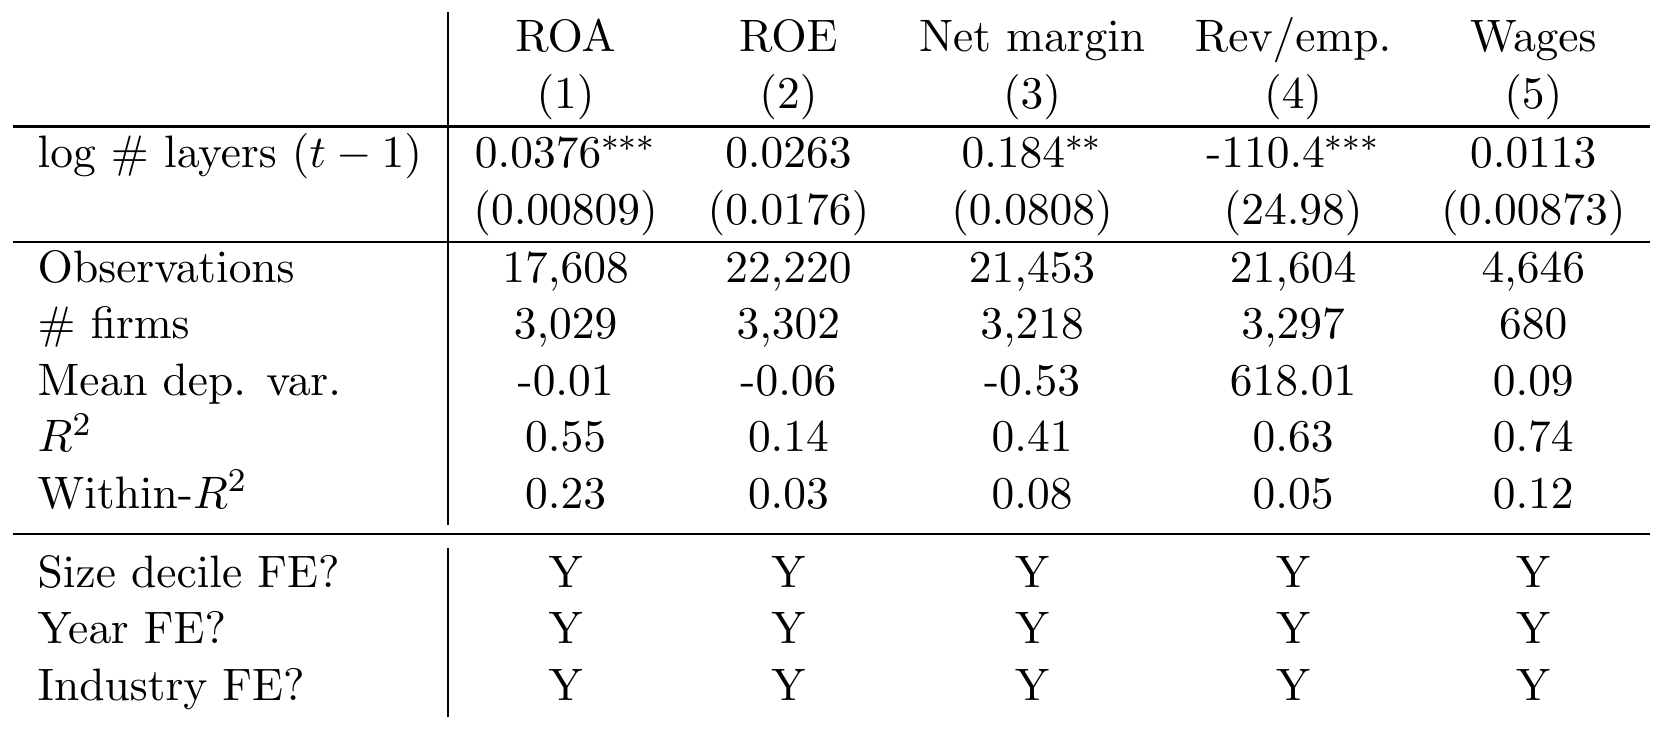
  • Higher ROA and net profit margin; ROE positive, not significant
  • Lower revenue per employee: more managers not directly involved in production
Columbia Business School
Corporate Hierarchy

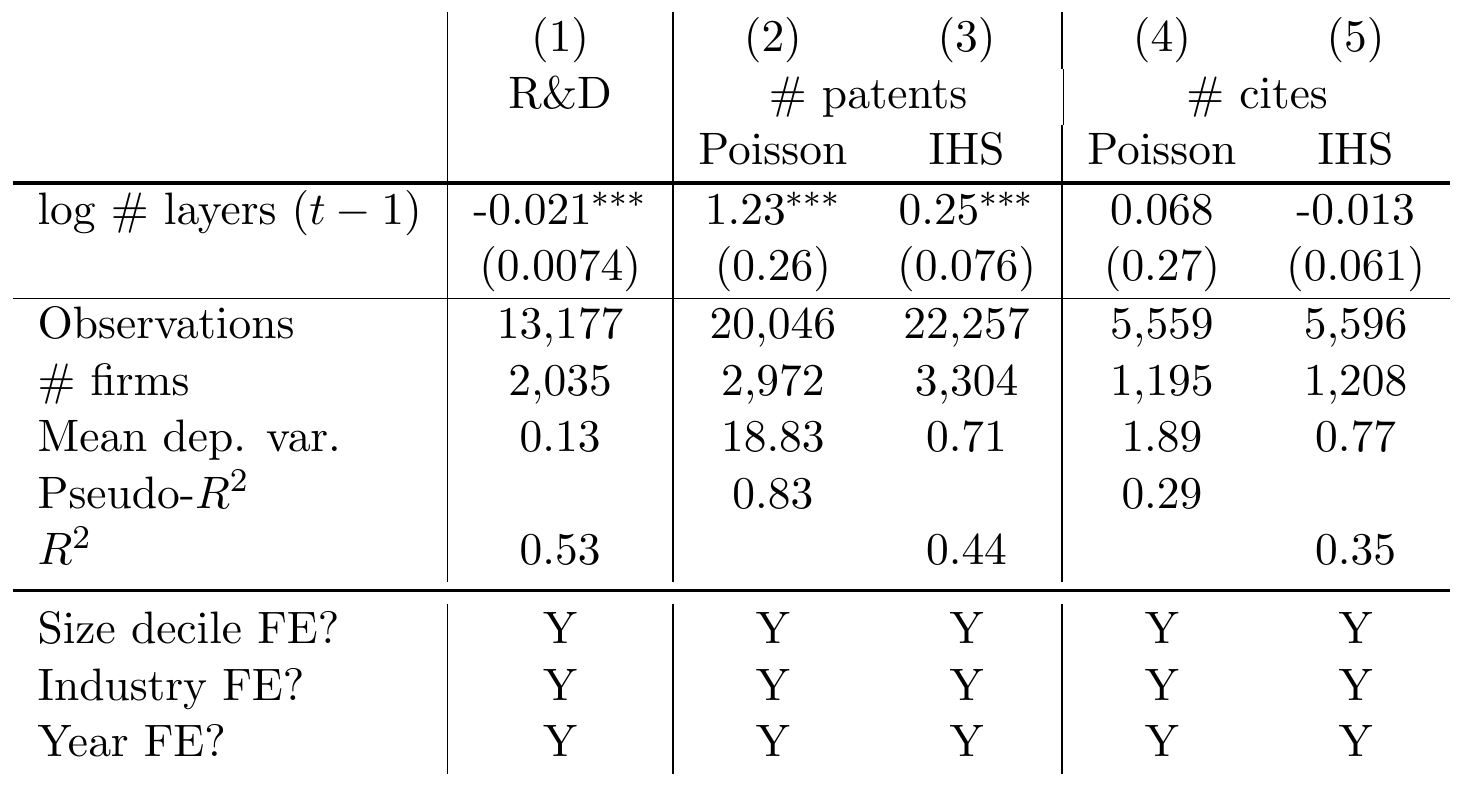
Innovation: less R&D, more patents, same quality

  • More layers does not correlate with worse patent outcomes
    • More efficient with R&D?
Columbia Business School
Corporate Hierarchy

Hierarchy and firm risk

  • Theories of corporate hierarchy give no explicit predictions for firm risk
  • In knowledge hierarchies, additional layers add problem solvers: better ability to manage risks and adjust to unexpected shocks
  • This would reduce the volatility of the firm’s cash flows
Columbia Business School
Corporate Hierarchy

More layers, lower stock volatility

  • More layers predict lower stock volatility
  • About 3% lower volatility for a 1 s.d. increase in log layers
  • Problem solvers may enhance the firm’s ability to manage risks
Stock σ
Wins.
(1) (2)
log # layers (t−1) -0.044*** -0.042***
(0.011) (0.010)
Observations 20,071 20,071
# firms 3,146 3,146
Mean dep. var. 0.54 0.53
R² 0.19 0.23
Size decile FE? Y Y
Industry FE? Y Y
Year FE? Y Y
Columbia Business School
Corporate Hierarchy

Business or financial risk?

  • Lower operating-asset volatility: business risk, not financial structure
  • No difference in debt; high-layer firms hold less cash
Operations and financial
σ(OA) σ(CF) Debt/Assets Cash/Assets
(3) (4) (5) (6)
log # layers (t−1) -0.033** -0.0063 -0.0024 -0.025***
(0.016) (0.0047) (0.011) (0.0083)
Observations 20,025 15,273 19,284 21,916
# firms 3,145 2,572 2,966 3,302
Mean dep. var. 0.40 0.04 0.28 0.23
R² 0.10 0.14 0.05 0.10
Size decile FE? Y Y Y Y
Industry FE? Y Y Y Y
Year FE? Y Y Y Y
Columbia Business School
Corporate Hierarchy

Flatter firms fared better in the Covid crash

  • Cumulative excess stock return over the Covid collapse period, Feb 3 – Mar 23, 2020 (Fahlenbrach et al. 2021)
  • All firms: more layers → larger decline, not significant
  • Covid industries (restaurants, hospitality, transportation): 10% more layers → about 0.7 percentage points larger decline
Cum. excess return, Feb 3 – Mar 23 2020
(1)(2)(3)(4)
Log # layers −0.014 −0.012
(0.016) (0.016)
Log # layers × Covid industry −0.073** −0.074**
(0.036) (0.035)
Log # layers × other industry −0.0015 0.0015
(0.017) (0.017)
Cash / assets 0.040 0.042
(0.027) (0.027)
Book leverage −0.18*** −0.18***
(0.025) (0.025)
Size decile FE? Y Y Y Y
Industry FE? Y Y Y Y
Observations 1,454 1,454 1,454 1,454
Mean dep. var. −0.36 −0.36 −0.36 −0.36
Adj. R² 0.23 0.26 0.23 0.27
Columbia Business School
Corporate Hierarchy
What explains layers
Moving hierarchy to the left-hand side
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

Layers are an investment

We have thus far taken layers as given, correlating with firm observables

  • Theory has a lot to say about how firms choose their hierarchy

Consider two explanations:

  1. Exposure to disruption → fewer layers
  2. Improvements in knowledge acquisition → fewer layers
Columbia Business School
Corporate Hierarchy

Product market threats: flatter hierarchies

  • Product market fluidity (Hoberg, Phillips and Prabhala 2014): how fast rivals’ products move into the firm’s product space
  • Firms facing more product market disruption have fewer layers, within industry too
  • Consistent with Guadalupe and Wulf (2010): competition from abroad removed management levels
Log # layers
(5)(6)
Product market fluidity −0.0080*** −0.0039**
(0.0013) (0.0016)
Size decile FE? Y Y
Industry FE? N Y
Year FE? Y Y
Observations 20,407 20,403
# firms 3,289 3,285
Mean dep. var. 1.81 1.81
Adj. R² 0.06 0.19
Columbia Business School
Corporate Hierarchy

AI: cheaper knowledge acquisition

  • Key prediction from Garicano (2000): lower the cost of knowledge acquisition – incorporating information and solving problems – lowers the need for layers
  • Lower layer workers can solve more problems themselves
  • Babina et al. (2024): identify when firms first post jobs for AI positions = proxy for AI adoption
Columbia Business School
Corporate Hierarchy

Introduction of AI: flattening of the firm

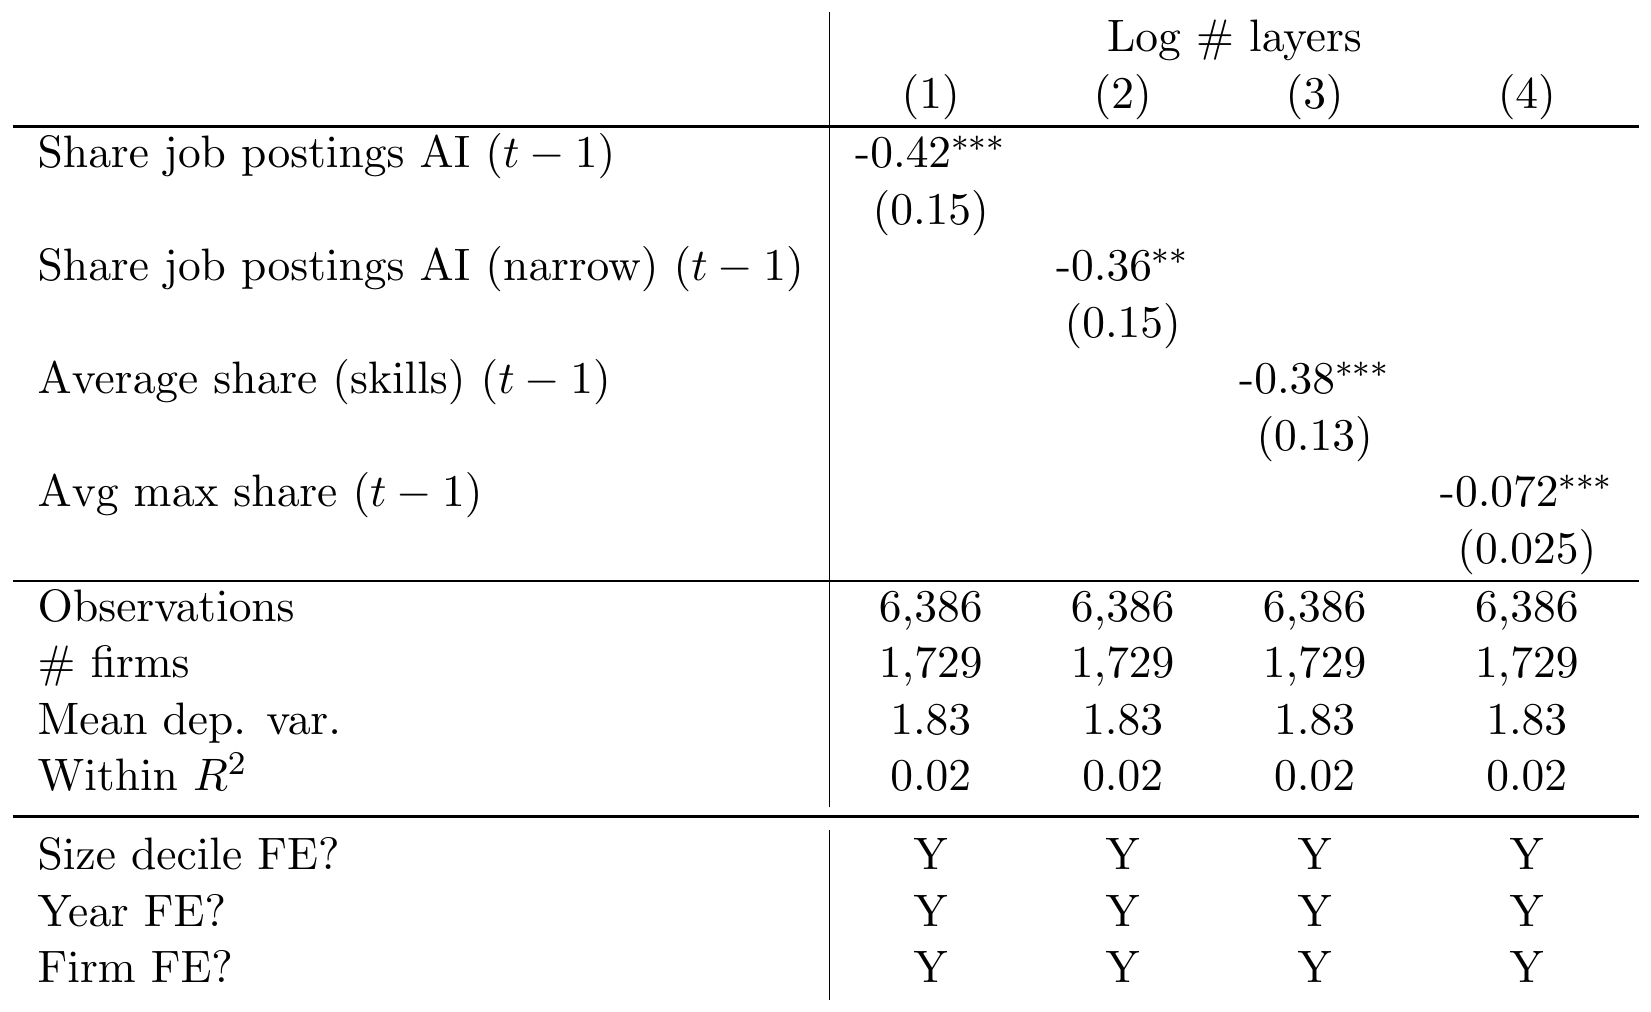
  • All four AI adoption measures predict fewer layers within the firm
  • Consistent with AI lowering the cost of knowledge acquisition and information processing
Columbia Business School
Corporate Hierarchy
Conclusion
Motivation
Theory
Measurement
Data and representativeness
Validation
Outcomes
What explains layers
Conclusion
Columbia Business School
Corporate Hierarchy

Hierarchies: measurable and important

  • Public workforce information reveals the firm’s hierarchy
  • Novel, data-driven measure for 3,454 US public firms
  • Benefits: workforce tied to the firm, operating performance, patent output, lower volatility
  • Costs: revenue per employee falls (more managers not directly involved in production); flatter firms weathered the Covid shock better
  • Firms flatten when facing product market threats or adopting AI
Columbia Business School
Corporate Hierarchy
Appendix
Columbia Business School
Corporate Hierarchy

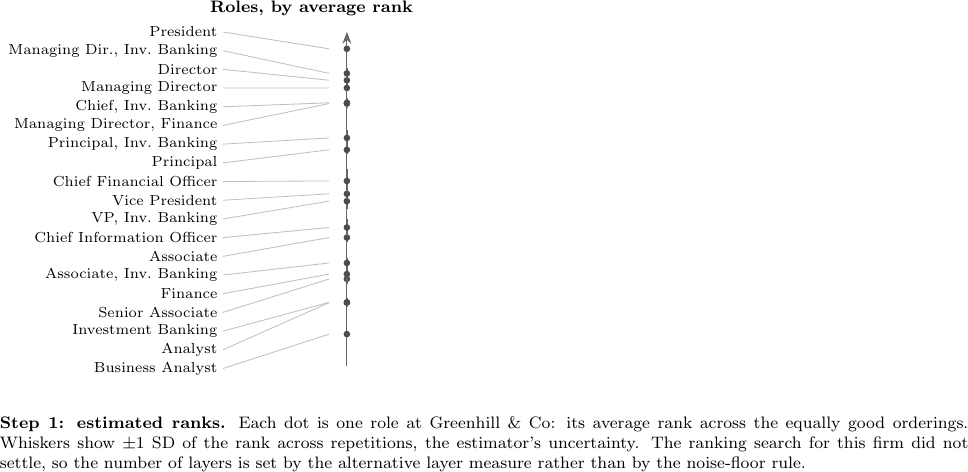
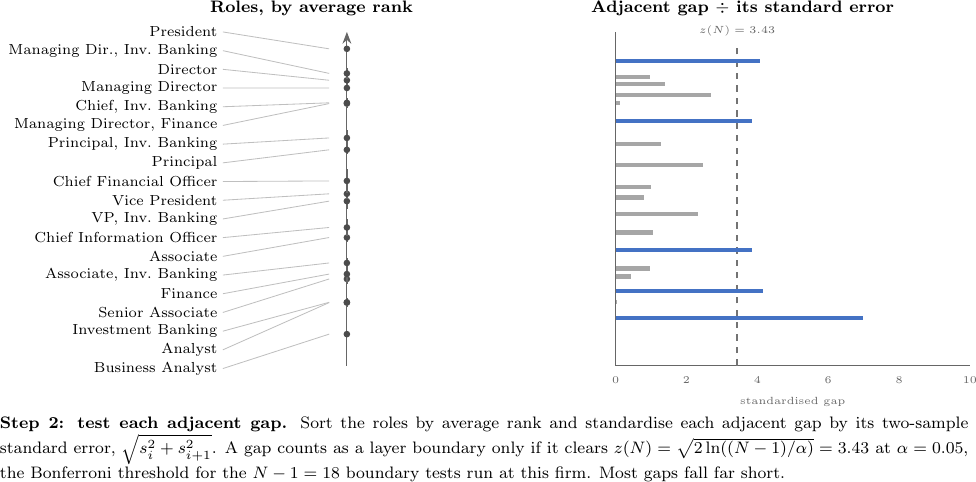
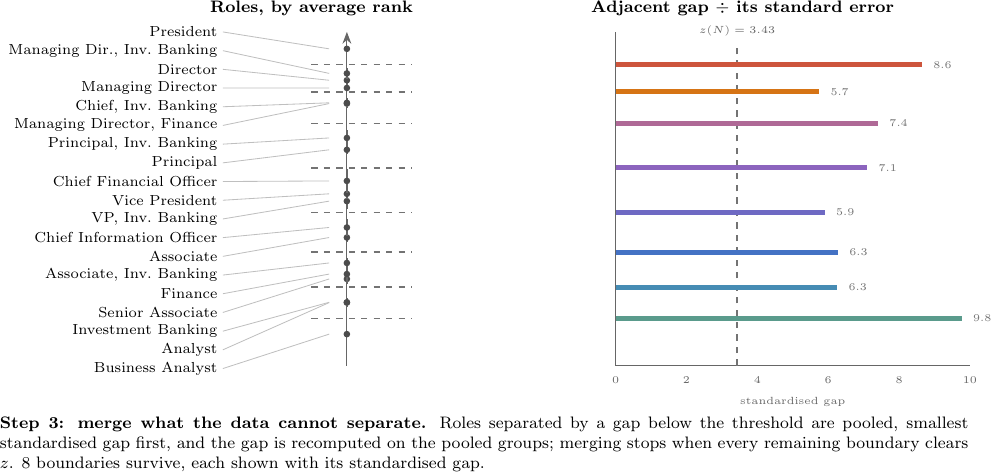
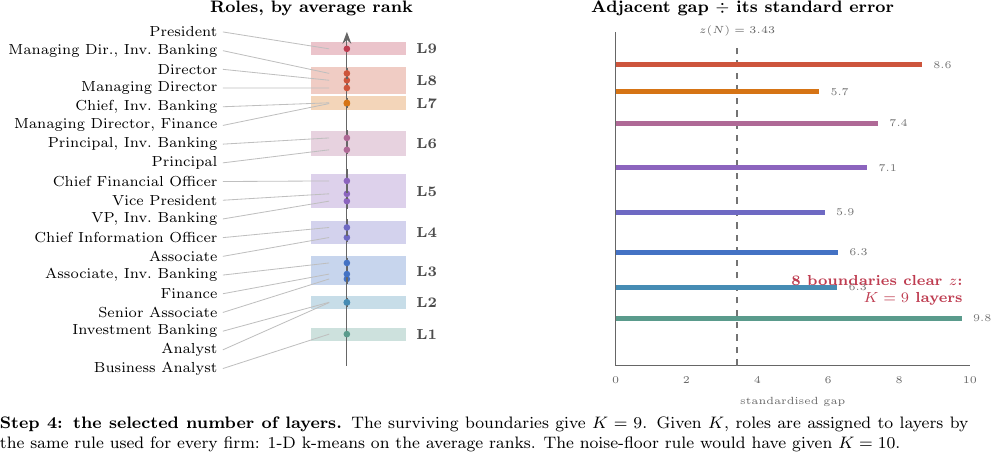
The alternative rule: Greenhill

  • Large promotion-heavy firms with many incomparable roles: the search does not settle
  • Alternative rule: merge neighboring roles until gaps exceed the Bonferroni family-wise threshold
  • Supplies K for 1,492 firms (43%)
Columbia Business School
Corporate Hierarchy

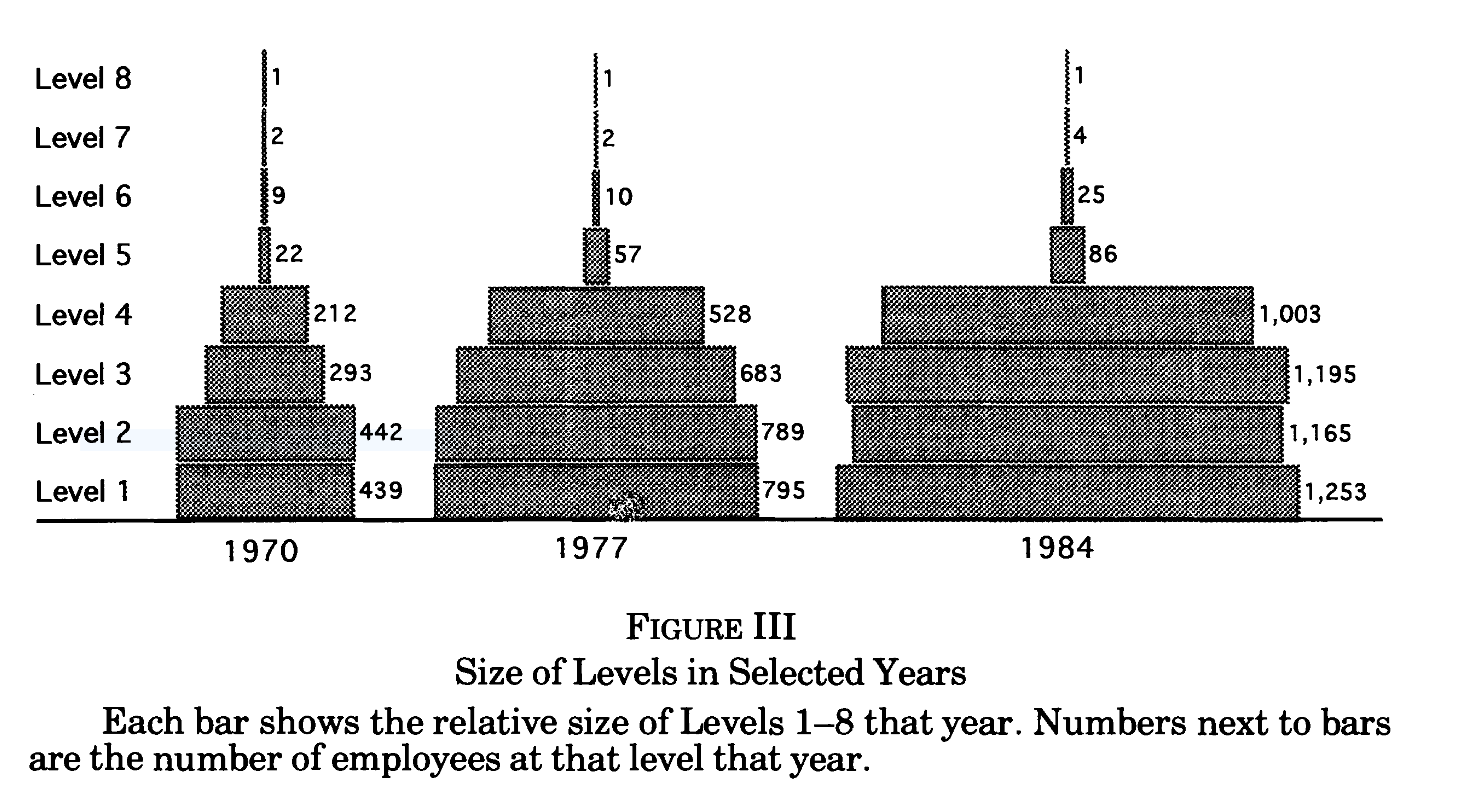
Baker et al.: from layers to firm shapes
Columbia Business School
Corporate Hierarchy

Simulator
Columbia Business School
Corporate Hierarchy

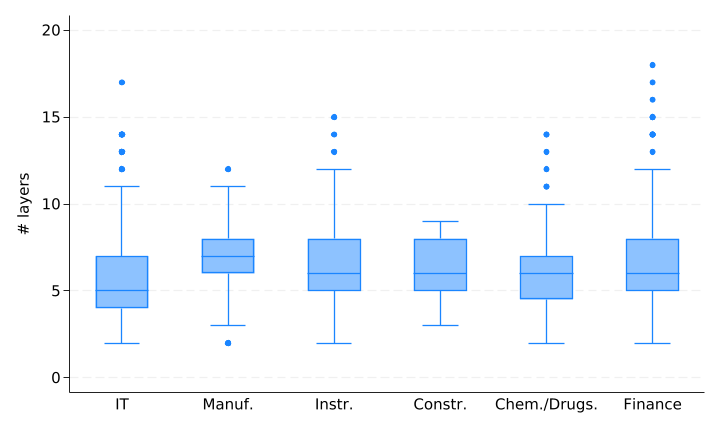
Industry variation of hierarchical layers

  • Few papers predict hierarchy differences by industry
  • Stein (2002): banks with more soft information should have fewer layers (“decentralized”)
Columbia Business School
Corporate Hierarchy

BLS appendix tables
Columbia Business School
Corporate Hierarchy

Bank ladders: step-three robustness

[TABLE PENDING: numbers/bank_ladder_v475onetj.tex, step three]
Columbia Business School
Corporate Hierarchy

Does missingness bias the count? Simulation

  • Synthetic firm with known structure; degrade coverage the way LinkedIn is incomplete; re-run the estimator
  • At the measured gaps, the true layer count is recovered; breaks only at extreme truncation
Columbia Business School
Corporate Hierarchy

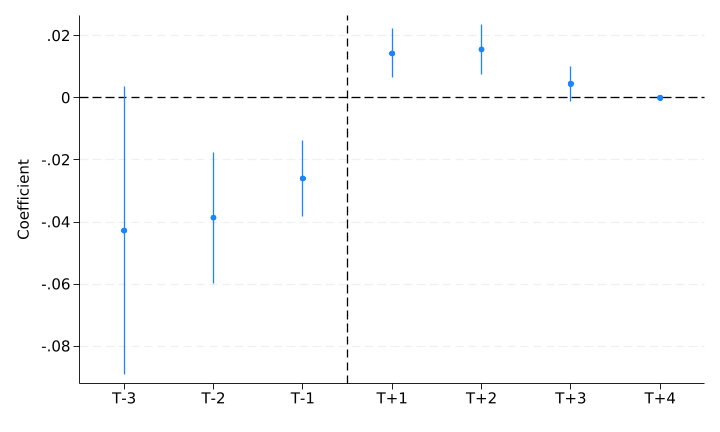
Going public: more layers after the IPO

  • Bernstein (2012); Bias et al. (JF 2026) German hierarchization
Columbia Business School
Corporate Hierarchy